Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY closed at 769.71 sitting just under the gamma flip at 771.60 - dealer positioning is Negative Gamma, meaning any move gets amplified rather than dampened until spot recaptures the flip. Key levels for Monday: call wall at 780.00 caps upside, put wall at 760.00 is the acceleration threshold, and the highest-OI cluster at 525 acts as a deep magnet on any washout. Dealers are carrying negative vex (-$175.46B) and negative charm (-$1M) - a vol pop will force delta selling, and unpinned decay pressure leans lower into next week. On the vol side, VIX at 14.52 inside steep contango (Contango) with VVIX at 84.51 still in the Low bucket says the market is not paying up for tail. VRP is positive at 1.37% - options remain rich to realized. Bottom line: fade extreme moves toward the walls, avoid naked directional premium, favor Iron Condor in the 30-45 DTE window, and size Standard Size.
Close-wrap: index complex sits below gamma flip in negative gamma, VIX contango steep
The cash session closed with SPY, QQQ, and IWM all sitting fractionally below their gamma flip levels - a knife's-edge negative gamma regime where any Monday gap either releases dealer buying or accelerates a downside impulse. Yet the vol complex is not confirming panic: VIX at 14.52 inside steep contango, VVIX still Low, and F&G registering Fear rather than fear. That divergence - destabilized microstructure paired with a sanguine vol surface - defines the setup and dictates the trade menu.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
769.71
771.60
-0.25%
780
760
760
-$1.31B
Short gamma
QQQ
718.33
718.57
-0.03%
730
700
705
$12.16M
Short gamma
IWM
295.83
295.94
-0.04%
300
290
290
-$2.27B
Short gamma
VIX
14.52
14.52
+0.02%
20
14.50
19.50
$16.49M
Long gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
9.50
8.13
+1.37
1.72
2.63
1.21
QQQ
13.67
12.85
+0.82
1.65
1.39
1.00
IWM
13.07
12.14
+0.93
1.88
2.44
1.27
VIX
80.11
78.28
+1.83
-140.81
0.38
0.21
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
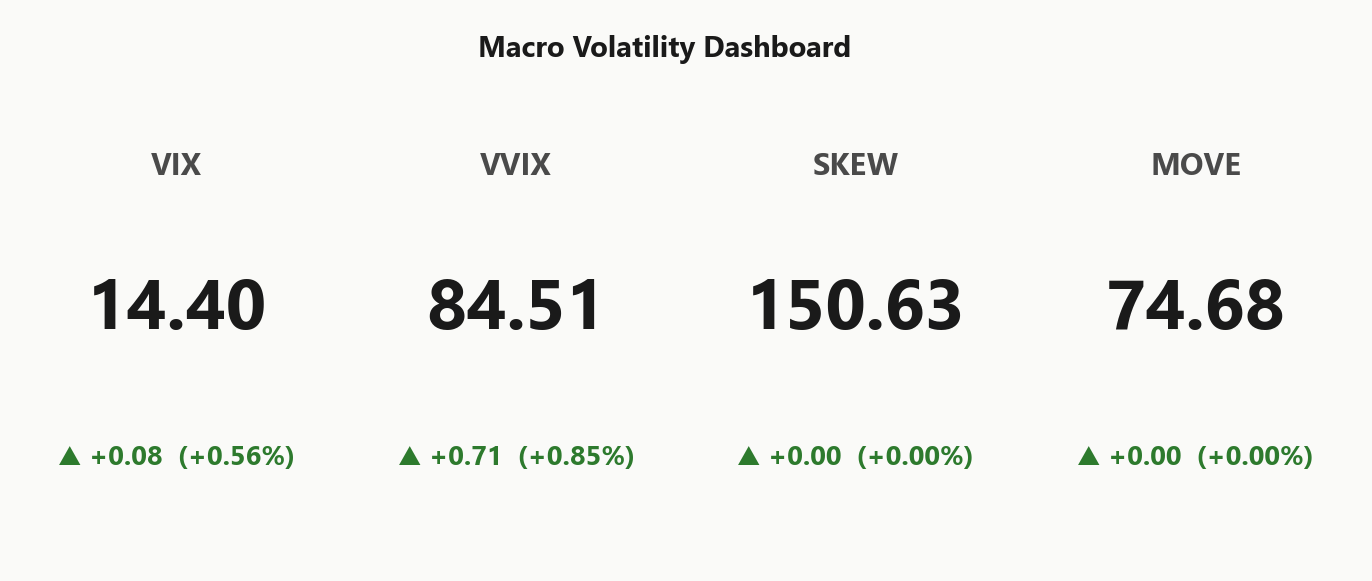
14.40
+0.56%
VVIX
84.51
+0.85%
SPX
7,718.60
-0.38%
SKEW index
150.63
0.00%
MOVE (bond vol)
74.68
0.00%
VIX term (9d/30d/3m/6m)
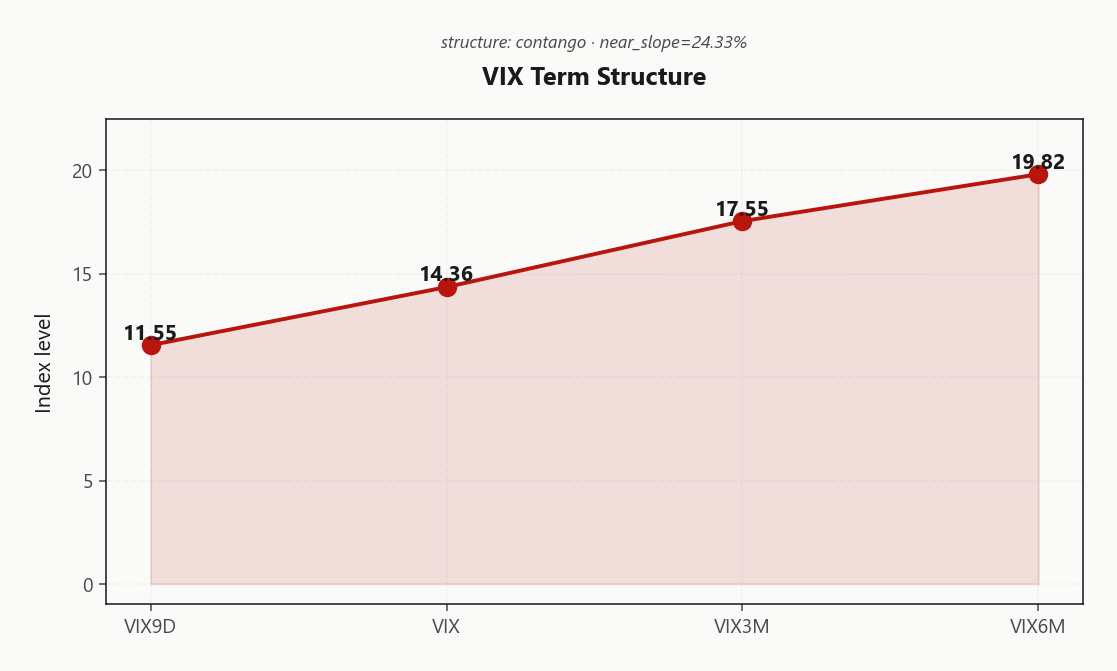
11.55 / 14.36 / 17.55 / 19.82
Steep contango
VVIX / VIX
5.87
Low
Regime
Low / Carry
Regime Assessment
The macro vol regime prints Low / Carry with VIX anchored at 14.40 - a carry environment where premium sellers get paid and tail hedgers bleed theta. Half-life of 30 sessions is the load-bearing statistic here: this state doesn't flip on a whim, it grinds. Base case into next week is persistence, not transition.
Transition probabilities confirm the read. P(→ panic in 5 sessions) sits at just 0.05 - the tape would need a genuine catalyst, not a wobble, to break this regime higher on vol. P(→ low in 10 sessions) at 0.45 says the more likely path is deeper into carry, not out of it. Combine that with steep contango and a Low VVIX print and the setup rewards short-vol structures sized standard.
The tension: dealer positioning at the index level reads Destabilizing while the macro regime reads carry. Micro-fragility inside a sticky low-vol frame - fade extremes, don't chase them.
What it means for your trading
Sticky Low / Carry regime with VIX at 14.40 and a 30-session half-life - persistence is the base case, transition to panic in five sessions is only 0.05. Trade the carry, respect the micro-fragility.
Trading readVIX up, VVIX up modestly, MOVE flat, SKEW elevated - the equity vol complex is confirming itself but the rates complex is not. That divergence caps how far equity vol can extend without a rates confirmation.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX complex prints textbook Contango from front to back - 11.55 at the nine-day, 14.36 at the thirty-day, 17.55 at three months, and 19.82 at six. Front-end suppression is being financed by term-structure sellers further out, and the near-slope carry pocket at 24.33%% is the widest concession on the curve. This is a carry regime, not a stress regime - the market is paying to be short front vol.
The forward 30-to-60 vol prints 18.9446285263, and the forward 60-to-90 extends to 21.8554867253 - a clean linear extrapolation with no kink, no dated event premium, and no bump anywhere the calendar can fade. That forward 30-to-60 anchor is the fair-value line calendar sellers should mark against; anything selling below it is giving away theta, anything above pays for the roll-down.
Regime read: Steep contango - vol sellers favored. Vol sellers favored, term-structure roll-down is the trade, and the belly of the curve is where the edge lives.
What it means for your trading
Steep Contango with no event kink means the curve is pure carry - sell front-belly vol against the 18.9446285263 forward anchor and let term-structure roll-down do the work.
Trading readSteep contango front-to-back - vol sellers of the front end being paid by term-structure buyers of the back. Historically this shape breaks first, not the equity tape - watch for slope flattening as the early tell.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
Variance premium remains intact across the index complex into the close. SPY ATM IV at 9.5% sits materially above HV20 at 8.13 and HV60 at 12.57 - options are pricing a tape that has not yet realized. VRP holds positive at 1.37%, confirming premium sellers are still being paid despite the negative-gamma microstructure underneath.
Cross-index, QQQ carries the fattest VRP of the majors at 0.82% - the summer realized burst in tech has faded faster than the IV surface has repriced, opening the widest HV-to-IV gap of the complex. IWM is the mirror image: ATM IV at 13.07% is not stretched against HV60 at 14.78, VRP a lean 0.93% - small-caps are not over-hedged, so the carry edge is thinner there.
Bottom line: index vol selling remains the paid trade, with QQQ the richest carry pocket and SPY the cleanest expression given liquidity. Trim size on IWM structures - the premium isn't there.
What it means for your trading
IV sits comfortably rich to realized across SPY and QQQ with VRP at 1.37% and 0.82% respectively - premium harvesting still edge-positive, with QQQ the widest carry pocket and IWM the least attractive at 0.93%.
Skew Convexity
The wing tape is unambiguous: SPY quarter-delta skew prints 1.72% with a smile ratio of 1.33% - puts bid 6.94% against calls at 5.22% and an ATM belly of 6.13%. Downside protection carries a real premium here; the right wing is flat, which means the options tape assigns zero conviction to upside convexity into next week.
IWM cuts the sharpest profile with quarter-delta skew at 1.88% - small-cap wings are the richest in the complex, consistent with the Negative Gamma print and the aligned cross-asset read at Aligned. Smile ratios above one across the index complex confirm wing demand is structural hedging flow, not tactical spec.
Trade implication: fade the wing, don't buy it naked. Put spreads and put ratios finance the expensive left tail; the flat call side makes call overwrites the cheaper directional expression. Skip lottery-ticket downside puts - you're paying peak vol for the exact strike everyone else is already long.
What it means for your trading
Steep put skew at 1.72% with smile ratio 1.33% means the wing is priced for stress the belly isn't confirming - sell the skew via spreads, don't chase it outright.
Vol-of-Vol Structure
VVIX prints 84.51 against a VIX at 14.40, dropping the ratio to 5.87 - squarely in the Low bucket. The vol-of-vol surface is not pricing bimodality: no jump premium embedded in front-month options, no convex tail bid layered on top of the equity vol move. The tape is treating this as a drift regime, not a gap-risk regime, and the VVIX complex is corroborating that read.
Cross-referenced against the Low / Carry regime and Steep Contango term structure, the message is consistent - carry environment, not stress environment. That gives premium sellers room to run Standard Size notional; the low VVIX print removes the primary reason to haircut short-vol structures. No convex tail bid means the wings you sell are unlikely to be repriced violently before decay does its work.
Trade implication: the recommended Iron Condor in the 30-45 DTE window can carry standard sizing without a jump-risk haircut. Only a VVIX pop through the mid-bucket would force a reassessment.
What it means for your trading
VVIX at 84.51 and a VVIX/VIX ratio of 5.87 confirm the market is not paying up for tail - short-vol structures can run Standard Size notional without a bimodal-risk discount.
Dispersion Spread
Index vol prints modest against the typical single-name premium - SPY ATM IV at 9.5% is carry-cheap relative to the mover cohort, and QQQ at 13.67% reinforces the read. Dispersion is muted but live: index vol is compressed while single-name HV60 has spiked in the NVDA/MSFT/META cluster driving the day's GEX shifts. The correlation trade is not screaming, but the asymmetry favors selling index vol over writing single-name overwrites.
Cross-strike dispersion sits moderate - no wing dislocation to arb, no obvious kink to fade. The preferred expression is index-level premium harvest (Iron Condor) in the 30-45 DTE window, where you collect the steep Steep Contango carry without paying up for single-name gamma that is realizing above its implied. Overwrite programs on mover names lose edge here - HV60 is doing the work IV is not.
What it means for your trading
Sell index vol, not single-name - SPY IV at 9.5% is the cheaper carry versus a mover cohort where HV60 has re-accelerated. Dispersion moderate, no wing edge, structure the trade at the index.
Liquidity & Microstructure
The strike map tells two stories at once: the highest open-interest cluster sits deep out-of-the-money at 525 - legacy positioning, not active-money - while the real magnetism is stacked at 760.00, where the put wall and max pain converge into a single gravitational pocket. That alignment is the honest read on where dealer books want spot to settle.
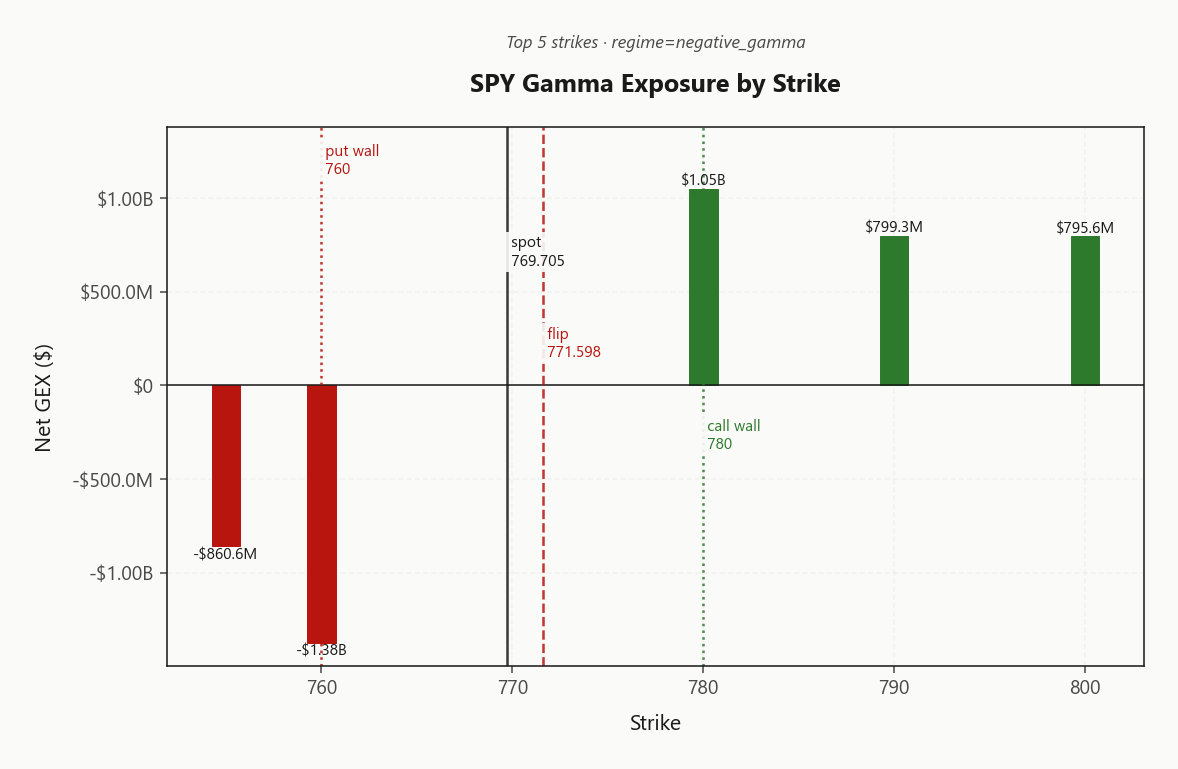
Gamma flip at 771.60 is the line. Spot at 769.71 sits fractionally underneath - a knife-edge Negative Gamma print where dealers amplify rather than dampen. The dominant negative-gamma pocket lives at 760.00 carrying -$1.38B, which is precisely the strike that acts as an accelerant on any Monday gap lower.
Rally attempts get capped at the 780.00 call wall; downside opens up through the put wall at 760.00. Trade the range from the walls in, not from the middle out - until spot reclaims the flip, every touch of the wall pays for a fade.
What it means for your trading
Spot pinned just below 771.60 with put wall and max pain aligned at 760.00 - the microstructure is knife-edge and amplifying, so fade the walls and treat any reclaim of the flip as the regime switch.
Trading readSharp negative-gamma pocket sits directly beneath spot and a stacked positive-gamma shelf above - asymmetric map where downside gets amplified and rallies hit an air pocket into the call wall.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Dealer books carry -$175.46B net vex and -$1M net chex into the weekend - a configuration where any vol pop mechanically forces delta selling and passive time decay leans the hedge lower without needing a spot catalyst. Vanna and charm are pulling in the same destabilizing direction as gamma, which is the tell: this isn't a one-greek problem, it's the whole surface aligned against a bounce.
The pivot that matters is the Gamma Flip at 771.598183522. Spot printing beneath it keeps current bias Destabilizing - flow amplifies moves rather than dampens them, and the signal is Red. Reclaim flips the entire book from accelerant to shock-absorber; failure to reclaim leaves Monday's opening tick sitting on a live vanna-charm feedback loop.
Trade the map, not the tape: treat rallies into the pivot as sell zones, size premium sales further out the curve where charm decay works for you, and avoid naked front-week short vol until spot is decisively back above the flip.
What it means for your trading
Vanna and charm are stacked on the destabilizing side of the book with spot beneath the Gamma Flip at 771.598183522 - rallies are sell zones until that pivot is reclaimed.
Cross-Asset Confirmation
Cross-asset tape refuses to confirm the equity wobble. MOVE holds at 74.68 - rates vol subdued, no credit dislocation, no macro shock priced. This is an equity-only micro-regime, not the leading edge of a broader risk event, and that distinction dictates how aggressively to hedge into Monday.
Sentiment tells the same story with a softer voice. Fear & Greed prints Fear at 42 - fading, not capitulating, and nowhere near the contrarian-buy extreme. QQQ at 718.33 and IWM at 295.83 both sit pinned beneath their gamma flips alongside SPY, leaving the complex in an Aligned regime with no divergent leader to lean on.
Cross-asset tone reads Unknown - the whole index book breaks or repairs together from here, without a rates or credit tell to front-run the resolution. Trade the equity microstructure on its own terms; do not pay up for macro-shock protection the rest of the tape is not corroborating.
What it means for your trading
MOVE at 74.68 and F&G at 42 confirm this is contained equity-microstructure weakness, not a cross-asset stress event. With QQQ and IWM Aligned beneath their flips, the complex resolves as one - trade the flip, not the tail.
Scenario EV
The setup screens as a textbook carry trade: Iron Condor ranks first with a composite score of 39, well ahead of the put-spread alternative at 26. VRP is intact at 1.37%, VVIX sits in the Low bucket, and the term structure is Contango - the three ingredients that make defined-risk premium selling pay.
The DTE window matters more than the strikes here. 30-45 lets you harvest term-structure roll-down from the 24.33% carry pocket without owning front-week gamma while spot sits a hair beneath the 771.60 flip. Front-week condors get punished by the Destabilizing dealer book; belly-DTE lets vanna and charm decay work for you rather than against.
Size Standard Size - VVIX at 84.51 is not pricing bimodal outcomes, so the trade doesn't need a tail-risk haircut. Anchor wings outside 780.00 and 760.00; those are where dealer flow caps the range.
What it means for your trading
Iron condor in the 30-45 DTE window is the trade - VRP-rich, low VVIX, steep contango is the classic setup, and belly-DTE sidesteps the negative-gamma front-week trap.
Actionable Summary
Bottom line: the trade is Iron Condor in the 30-45 DTE window - VRP is intact, VVIX sits in the Low bucket, and steep contango Contango pays you to sit inside the belly rather than own the front-week knife edge.
Watch 771.598183522 as the regime switch: reclaim and dealer flow flips from Destabilizing back to mean-reverting; lose it and the negative-gamma amplification stays live with net vex at -$175.46B feeding spot lower on any vol pop. Regime read is Low / Carry with a half-life of 30 sessions - assume persistence unless the flip breaks decisively.
Avoid naked front-week short premium; negative gamma paired with negative chex at -$1M punishes uncovered sellers. Size Standard Size - VVIX/VIX at 5.87 is not pricing jumps, so standard notional carries.
What it means for your trading
Trade the Iron Condor in 30-45 DTE, pivot on 771.598183522, and skip front-week naked premium while the complex sits below flip.
Hot jobs data reprices Fed hike odds - the primary reason the front end sold off and equity vol failed to confirm the tape weakness; watch 2Y for the next tell.
Second consecutive weekly equity fund outflow confirms the tape weakness is real capital rotation, not a positioning quirk - supply-demand headwind into next week.
Diesel record + refinery disruptions is an underappreciated inflation pass-through vector - could show up in CPI prints and reprice rate-cut odds further.
Oil holding weekly gain on Iran risk reinforces the energy-inflation feedback loop that's pinning yields higher and equity below the flip.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 14.52 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 771.60 against a spot of 769.71. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 9.5% with a volatility risk premium of 1.37%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 14.40. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime