Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY prints 772.83 sitting essentially on the gamma flip at 772.99 - net GEX still positive at $4.16B but the regime tag is Negative Gamma, meaning any slip below the pivot flips dealer flow from stabilizing to trend-amplifying. Call wall stacks at 775.00 with put wall support at 765.00, boxing the tape into a tight 756.00-anchored range for pinning. Dealers carry net negative VEX at -$202.61B and negative charm at -$1.6M - vanna is hostile if VIX pops from 14.31, charm bleeds into close. VIX term structure is steep contango - VIX9D 11.69, VIX 14.36, VIX3M 17.40 - with VRP at 0.69% vol above realized 8.34, so premium sellers are being paid. VVIX at 83.45 says no jump premium is bid - carry regime confirmed, sizing standard. Bottom line: sell 30-45 DTE iron condors between 765.00 and 775.00, but keep tail hedges on because a single close below 772.99 pivots dealer flow to accelerant and turns this into a chase.
Negative gamma at flip, VIX 14.31, steep contango - carry regime with fragile intraday tape
SPY at 772.83 is pinned within a whisker of the gamma flip at 772.99, so dealer hedging flips direction on the tick - a destabilizing microstructure inside an otherwise carry-friendly macro. VIX at 14.31 with steep contango into 17.40 rewards premium sellers, and VVIX at 83.45 confirms no jump premium is bid. The trade is short vol structured - iron condors between 765.00 and 775.00 - but sized for the fact that flip proximity turns any -5.79% vol pop into a directional squeeze.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
772.83
772.99
-0.02%
775
765
756
$4.16B
Short gamma
QQQ
717.42
718.16
-0.10%
720
700
705
$919.94M
Short gamma
IWM
295.09
298.25
-1.06%
300
290
290
-$3.30B
Short gamma
VIX
14.31
16.13
-11.29%
20
14
19.50
$40.57M
Short gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
9.03
8.34
+0.69
-152.76
2.55
1.07
QQQ
13.13
13.55
-0.42
-171.47
1.35
1.14
IWM
12.86
12.83
+0.03
1.01
2.55
1.90
VIX
119.71
77.82
+41.89
-131.31
0.37
0.52
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
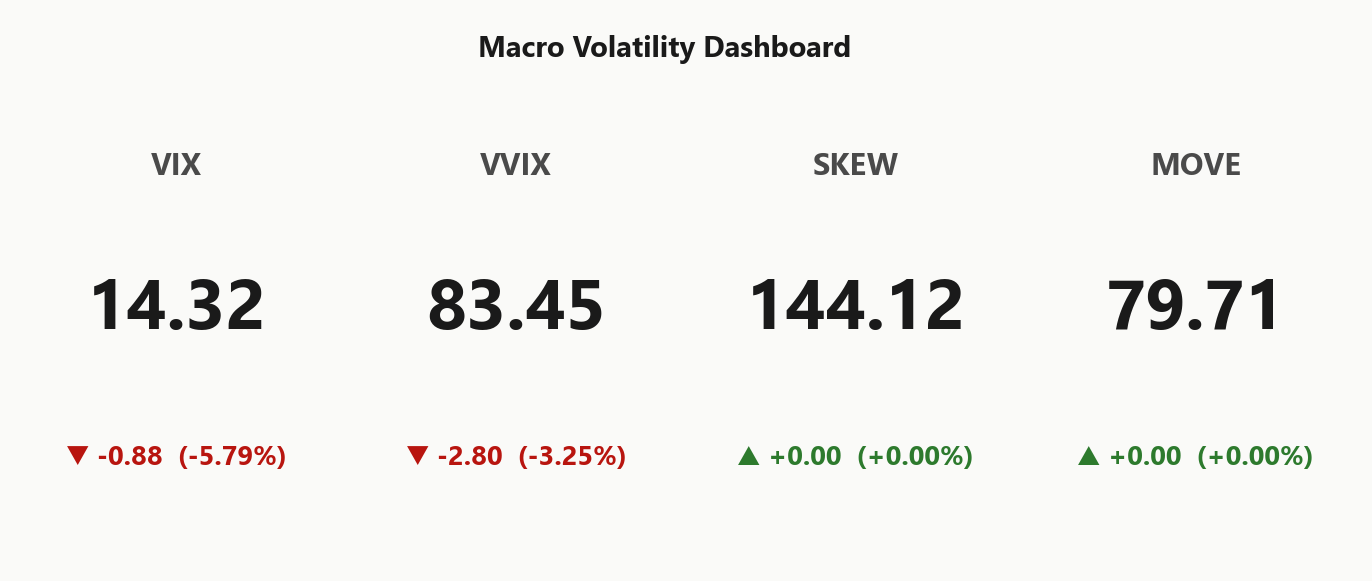
14.32
-5.79%
VVIX
83.45
-3.25%
SPX
7,747.71
+1.06%
SKEW index
144.12
0.00%
MOVE (bond vol)
79.71
0.00%
VIX term (9d/30d/3m/6m)
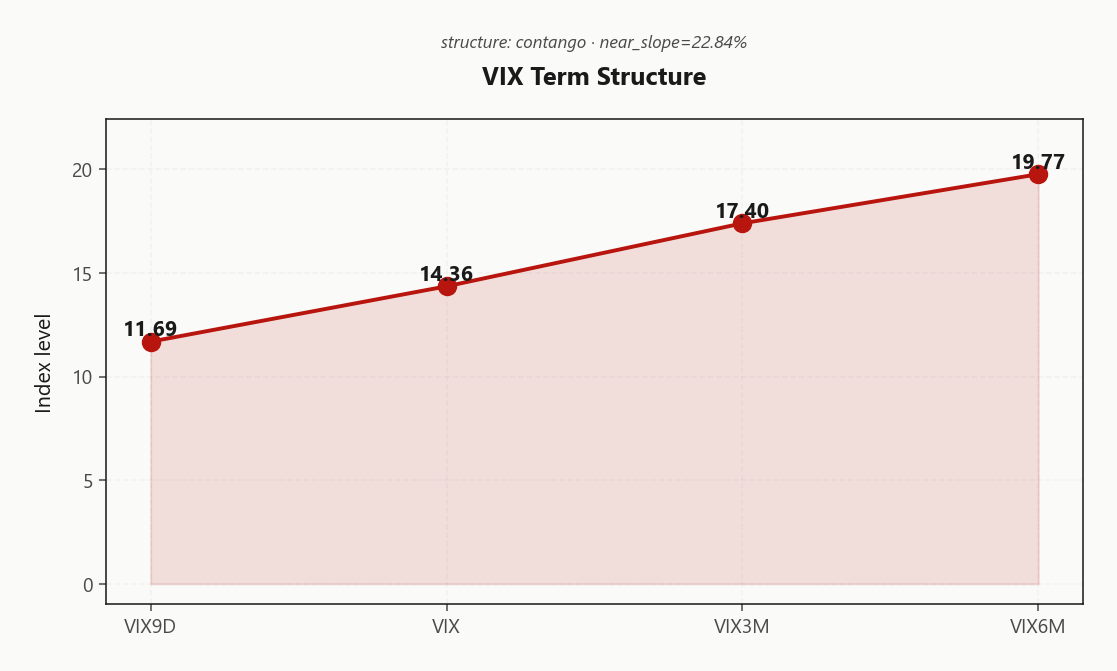
11.69 / 14.36 / 17.40 / 19.77
Steep contango
VVIX / VIX
5.83
Low
Regime
Low / Carry
Regime Assessment
The regime model tags the tape Low / Carry at a VIX print of 14.32 - carry-friendly and, critically, sticky. Half-life of 30 sessions means the probability of holding this state over the next ten sessions runs 0.45, so position sizing can be set once and left alone rather than churned session-to-session.
Durable is not permanent. The five-session panic transition probability still prints 0.05 - small, but not zero, and the pathways are visible: charm pivot is Destabilizing with spot within 0.0208855552% of the flip, and a VIX pop from 14.31 would light vanna hostility given net VEX at -$202.61B. Carry the trade, don't strip the tails.
Regime is Low / Carry with a 30-session half-life - steady sizing appropriate, but the 0.05 panic transition probability over five sessions keeps tail hedges non-negotiable.
Trading readVIX low, VVIX low, MOVE flat, SKEW mid-range - every dial confirms the same story. When macro dials align this cleanly, the risk is that a single tail catalyst repricings all four at once.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The term structure prints textbook Contango - VIX9D at 11.69 anchoring the front, VIX at 14.36, VIX3M at 17.40, VIX6M at 19.77. Near slope of 22.84%% is the tell: this is structural carry, not event pricing. When the front is this discounted relative to the belly, the market is paying you to be short front-month vol against longer-dated hedges.
Forward 30-60 vol lands at 18.7359333901 - flat expectations, no kink signaling a scheduled event bid. Regime tag reads Steep Contango with signal color Green. The sweet spot is the belly - 30-60 DTE forward vol is where the roll-down is cleanest and gamma decay is manageable. Sellers get paid across the curve; the trade is calendars long the belly, short the front, or straight front-month premium harvest if you can wear the gamma.
Caveat: near slope this steep is durable until it isn't. A single VIX9D rerate above 14.36 collapses the carry in a session.
What it means for your trading
Steep contango with near slope at 22.84%% and forward 30-60 vol at 18.7359333901 greenlights front-month vol selling with 30-60 DTE structures as the highest-quality carry expression.
Trading readSteep contango with front slope 22.84%% is a carry-regime signature - the market expects mean-reversion, not stress. Vol carry trades earn until the slope flattens.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
ATM IV prints 9.03% against a 20-day realized of 8.34, leaving VRP at 0.69% vol - a thin cushion, not a fat one. Premium sellers are still edged, but the spread is narrow enough that a single wide-range session flips the sign and turns the carry trade into a mark-to-market bleed.
Short-window realized is the tell: RV5 at 11.11 sits above the 20-day print, so actual movement is drifting up into an IV bid that has not yet followed. The Thin Premium tag confirms it - options are mildly rich to delivered vol, but the buffer is a coin-flip session away from disappearing.
The redeeming layer sits further back on the curve: longer-window vol regimes ran hotter, and the mean-reversion path favors the carry side of the trade. Sell the premium, but size to what a two-sigma day costs - not to what the current VRP implies.
What it means for your trading
VRP at 0.69% vol is real but thin - premium sellers keep the edge on an Thin Premium read, yet one wide-range close flips the sign. Size to the tail scenario, not to the headline spread.
Skew Convexity
Front-week skew screens dislocated at -152.76% with a smile ratio of 0.07%, but the tape is lying to you - the 1DTE call wing at 165.02% is a dislocation artifact, not a directional bid. Strip that noise and the picture inverts: put 25d IV prints 12.26% against ATM at 12.32% - near parity, meaning nobody is paying up for downside on the front week.
The smile ratio confirms it: downside is not being bid panic-style. Structural expiries show an orderly tail, not the convex bulge that would flag hedgers reaching. Combined with VVIX at 83.45 and the Steep Contango term structure, the whole vol surface reads as calm-with-a-fragile-pivot rather than pre-shock.
Trade implication: put spreads over naked puts. When the tail isn't being bid, you're not compensated for outright long-gamma downside - spread the risk, cap the debit, keep the convexity where it's cheap on the wing rather than in the body.
What it means for your trading
Headline skew is noise; adjusted for the 1DTE call-wing dislocation the surface is orderly and downside is not panic-bid. Buy convexity via put spreads, not naked puts - the tail isn't paying you enough to own it outright.
Vol-of-Vol Structure
VVIX prints 83.45 against VIX 14.32 for a ratio of 5.83 - classified Low. Translation: the vol surface is not paying up for jump risk. There is no bimodal outcome embedded in the tape, and the compression into the print (-3.25%) confirms sellers of convexity are still in control of the second moment.
The tactical read is nuanced. Straddle owners are effectively under-hedged for a spike - cheap vega, cheap gamma, cheap tail - but the same read gives premium sellers a green light to run Standard Size. The market is pricing continuity, and the vol-of-vol tape is corroborating what the term structure and VRP already said: this is a carry regime, not an event regime.
Sizing guidance is Standard Size - full clip on the recommended Iron Condor. The caveat: a benign VVIX is the same signal that leaves tail hedges cheap, so keep the wing on. When vol-of-vol is bid, it is too late to buy it.
What it means for your trading
VVIX at 83.45 with ratio 5.83 greenlights Standard Size on short-vol structures - but the same read means tail hedges are cheap and should stay on the book.
Dispersion Spread
Index ATM IV at 9.03% is meaningfully suppressed against single-name IV in the tape's dominant movers - NVDA and TSLA carry retail-heavy positioning that keeps their vol bid well above what index dispersion at 82.02 implies. That's not just a vol read, it's a correlation signal: the crowd is paying up for idiosyncratic convexity in AI-adjacent names while under-pricing coincident index moves. Cross-strike dispersion at 82.02 vs cross-expiry at 3.28 confirms the geometry - the gap lives at the strike axis, not the term axis.
Trade the pricing gap directly: sell SPY/SPX vol for premium harvest where index IV cheapness compounds the 0.69% cushion, and buy single-name convexity in the AI-adjacent movers as directional expression - not as index hedge. The two legs are not offsets; the single-name buys are a lean on the narrative bid, sized to convexity payoff, not to variance-neutrality against the short index book.
What it means for your trading
Index vol at 9.03% is a correlation trade dressed as a vol trade - sell SPY/SPX premium, own single-name convexity in NVDA/TSLA as directional expression rather than hedge.
Liquidity & Microstructure
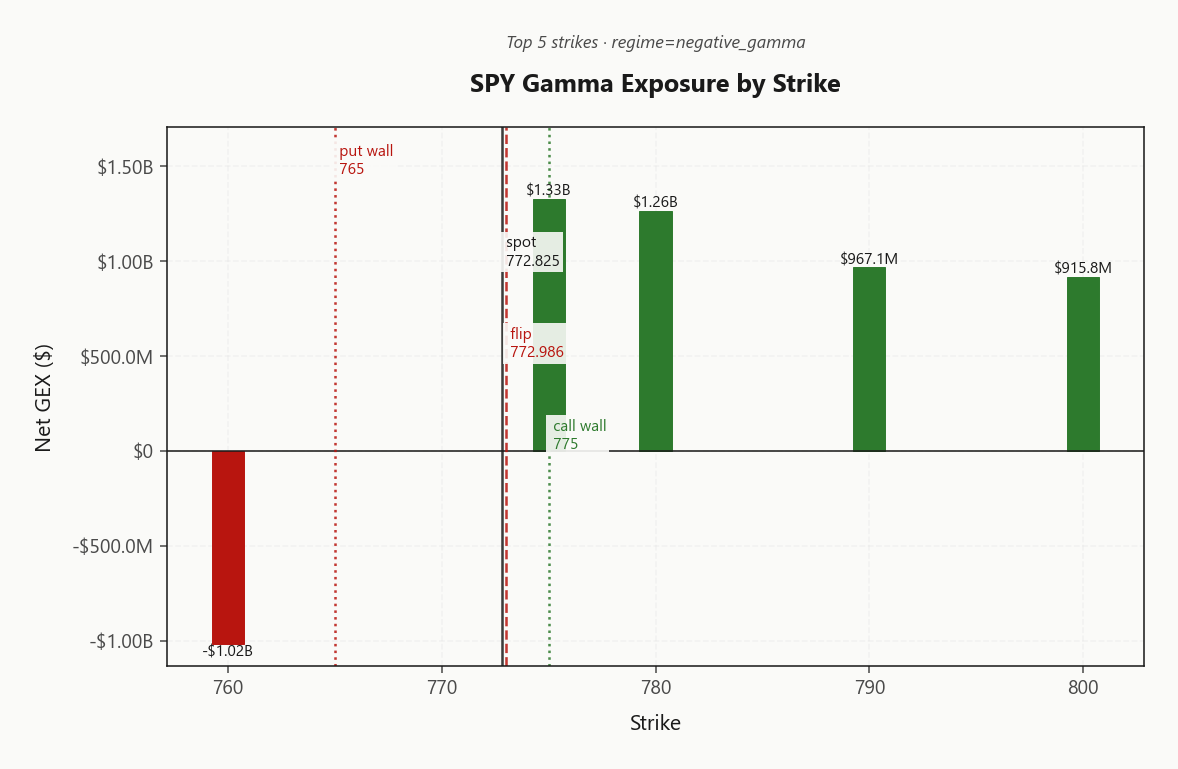
Open interest anchors at 525, but that's legacy positioning - the live fight is between the 765.00 put wall and the 775.00 call wall, with spot pinned inside a whisker of the 772.99 gamma flip. The top strike at 775.00 carries $1.33B of net GEX, so dealer buying stabilizes rallies only while the tape holds above the flip.
Distance to pivot reads 0.0208855552 - knife's edge. Above 772.99, dealers dampen and range-trade the book toward 775.00; a close below inverts flow to trend-amplifying and opens a mechanical path toward 765.00. The call wall is the ceiling dealers defend, the put wall the floor they buy - everything in between is pin-eligible.
What it means for your trading
Structure is deep but the pivot at 772.99 is the entire trade: hold above and dealer flow is your friend, close below and the same book turns accelerant into 765.00.
Trading readGamma stacks positive between 765.00 and 775.00 but the tape sits right on the flip - dealers dampen intraday only while spot holds above 772.99, and any close beneath flips flow to trend-amplifying.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
The vanna line is the one to respect: a pop in VIX from 14.31 forces dealers to sell delta into the move, and with net VEX at -$202.61B that mechanical hedge is not small. Charm compounds the problem into the bell - decay drips dealer supply steadily as the session ages, turning benign afternoon drift into a one-way skid if the pivot fails.
Trade the flip, not the tape. Above 772.9864087923, carry structures work; below, vanna and charm align against you and short-strangle risk explodes.
What it means for your trading
Vanna and charm are both hostile with spot within 0.0208855552% of the pivot at 772.9864087923 - a VIX pop from 14.31 or a close through the flip converts dealer hedging from dampener to accelerant.
Cross-Asset Confirmation
MOVE prints 79.71 - bond vol calm, credit-adjacent stress conspicuously absent. Fear & Greed sits at 35 in Fear, a contrarian bullish tell: sentiment lags a tape that keeps grinding, and the crowd hasn't chased the rally yet.
QQQ at 717.42 and IWM at 295.09 both carry the same negative gamma tag as SPY - regime divergence reads Aligned. Alignment, not rotation, is the story. When indices move in lockstep with VIX in contango and MOVE flat, the driver is macro flow, not sector dispersion - and the risk shifts from a rolling correction to a coordinated repricing if a single catalyst hits.
Cross-asset tone reads Unknown. Nothing in credit, rates, or vol-of-vol is bidding the tail - but that same coherence means every dial repricings together if the geopolitical bid on energy finally bites. Standard sizing, hedges retained.
What it means for your trading
Cross-asset dials align - MOVE calm, F&G at 35 contrarian bullish, QQQ and IWM both negative gamma alongside SPY. Alignment is the signal: no panic, but no diversification either if the tape cracks.
Scenario EV
The scoring engine tags Iron Condor as the optimal structure at score 33 across the 30-45 DTE window - VRP running 0.69% vol above realized, VVIX benign at 83.45, and term structure locked in Contango is the textbook premium-harvest setup. Sell the wings between 765.00 and 775.00, let charm and carry do the work.
Put spread also scores 33 - equal weight to the condor and the cleaner trade if you carry a directional lean, since the flip at 772.99 is the accelerant level and downside asymmetry compensates for skew paid. VRP assessment reads Unknown and the composite prints Standard Size - yellow light, not green. Size to what a two-sigma day costs, keep tail hedges live, and don't strip protection while spot sits within 0.0208855552% of the pivot.
The trade is Iron Condor on 30-45 DTE, structured between the 765.00 put wall and 775.00 call wall. Regime reads Low / Carry with VIX at 14.31, VVIX at 83.45, and term structure in Contango - every dial confirms sellers get paid. VRP at 0.69% is modest but positive; Standard Size per the vol-of-vol read.
The pivot is 772.9864087923. Spot sits within a whisker - dealer bias is Destabilizing at flip proximity, so a close beneath inverts flow from dampening to trend-amplifying and turns any -5.79% vol pop into a directional squeeze via Vol up = dealers sell delta - downside amplified if vol spikes vanna. Avoid naked short strangles into that flip - vanna hostility punishes them. Avoid chasing prints above 775.00; that's the dealer sell ceiling. Keep tail hedges on despite the 30-session regime half-life - the panic transition probability is not zero.
What it means for your trading
Sell the Iron Condor between 765.00 and 775.00 on 30-45 DTE at standard size, but treat 772.9864087923 as a hard pivot - a close beneath flips dealer flow to accelerant and inverts the entire thesis.
Retail options volume erupting on Robinhood and Tesla in the historically worst month for stocks - a positioning signal that dealer short-gamma exposure to single-names is building, feeding the negative-gamma tag on the index.
Oil rising on Middle East escalation is the tail-risk on today's F&G Fear print - energy shock is the credible catalyst that can crack the steep contango.
US pressure on Iran biting is the compounding macro thread with oil news - geopolitical bid on energy is the pathway from low VVIX to a fast MOVE repricing.
US strikes killing Iranian military personnel escalates the geopolitical tail - direct kinetic action raises the probability of the panic transition over 5 sessions that the regime model puts at 0.05.
Iran warning against Israeli attack on Hezbollah-held ground extends the escalation window - vol markets have not priced this; watch VIX contango for first sign of unwind.
Broadcom CEO's bullish long-term AI targets and Snowflake earnings reinforce the AI-narrative bid that sits underneath NVDA's GEX shift - this is the demand-side story keeping the tape carry-friendly.
ECB expected to raise a second time in September then pause - rate path clarity supports the carry regime by removing central bank surprise as a vol catalyst near-term.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 14.31 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 772.99 against a spot of 772.83. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 9.03% with a volatility risk premium of 0.69%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 14.32. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime