Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY sits at 762.79 with net GEX at -$4.65B - squarely in Negative Gamma territory below the 766.66 flip, meaning dealers must sell weakness and buy strength (trend-amplifying, not mean-reverting). Call wall stacks at 765.00 and put wall at 760.00, with the heaviest OI cluster at 760.00 acting as the day's magnet. Dealer vanna at -$101.4B is hostile - any vol spike accelerates delta selling - while charm bleed pressures dealers to sell into the close. Vol read: VIX 15.91 with Contango term structure (VIX9D 14.33 → VIX3M 18.33) keeps carry rich, VRP at 3.62% confirms options paid over realized. VVIX at 89.94 is contained but rising (4.23%% today) - tail hedges still cheap. Fear & Greed at Fear (31) is a contrarian tailwind for premium sellers. Bottom line: sell Short Put Spread in 21-30 DTE below 760.00, but keep sizing standard - respect that we're below flip and one gap can trigger the vanna cascade.
Negative gamma across index complex with VIX contango - dealers amplify moves but vol carry favored
SPY trades at 762.79 in Negative Gamma territory with spot below the 766.66 flip - dealers are forced to sell into weakness and chase strength. Meanwhile VIX at 15.91 with steep Contango says the vol curve is paying sellers, but VVIX at 89.94 and Fear & Greed at Fear warn the calm is uneasy. Best edge: short put spreads in the 21-30 DTE window while dealer amplification keeps intraday ranges wide.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
762.79
766.66
-0.50%
765
760
756
-$4.65B
Short gamma
QQQ
706.88
713.90
-0.98%
710
700
704
-$4.06B
Short gamma
IWM
292.73
297.85
-1.72%
300
290
290
-$4.18B
Short gamma
VIX
15.91
16.09
-1.15%
20
15
20
-$24.78M
Short gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
10.80
7.18
+3.62
-127.87
2.55
1.34
QQQ
15.81
13.17
+2.64
-135.00
1.36
1.51
IWM
15.49
12.02
+3.47
3.31
2.59
1.94
VIX
76.17
72.43
+3.74
-108.56
0.38
0.32
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
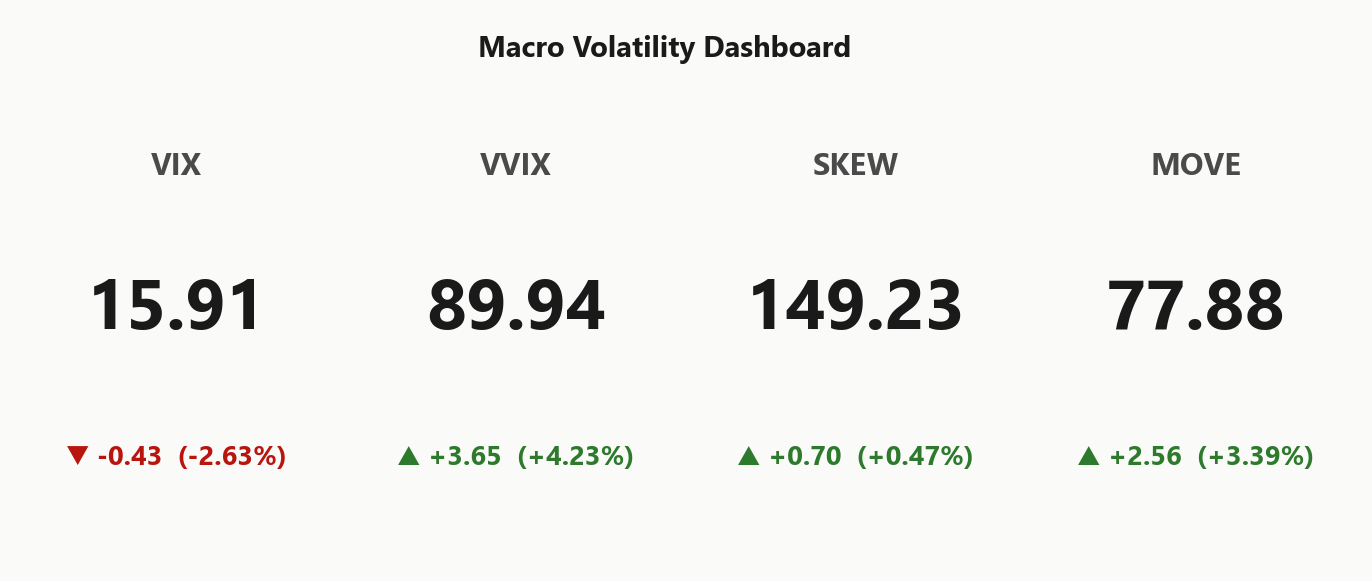
15.91
-2.63%
VVIX
89.94
+4.23%
SPX
7,644.10
+0.17%
SKEW index
149.23
+0.47%
MOVE (bond vol)
77.88
+3.39%
VIX term (9d/30d/3m/6m)
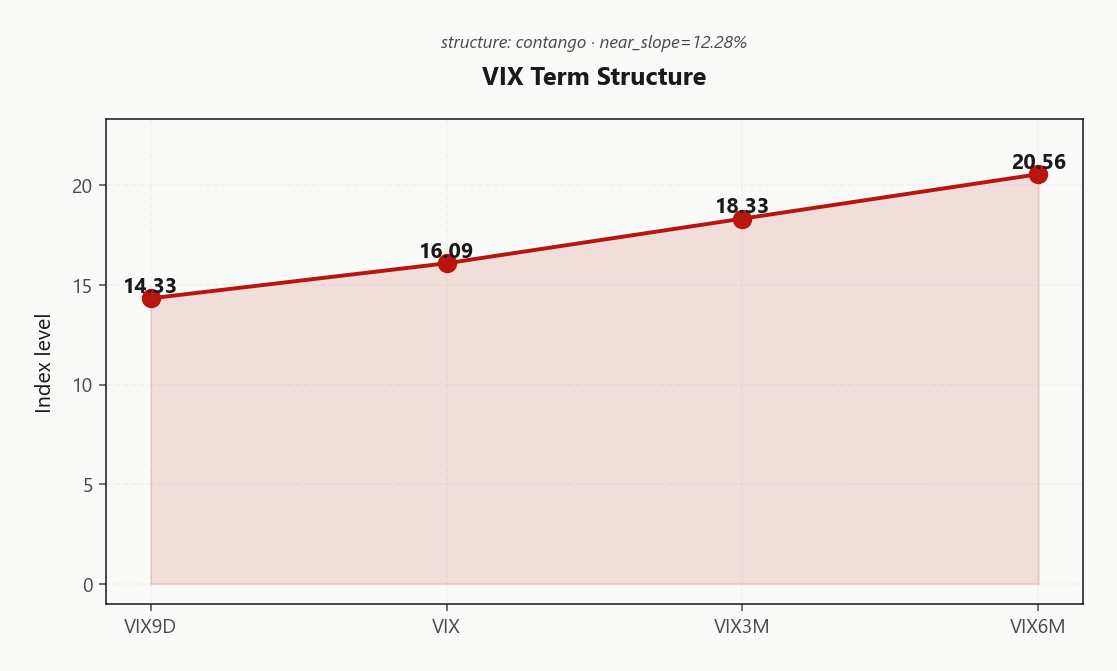
14.33 / 16.09 / 18.33 / 20.56
Steep contango
VVIX / VIX
5.65
Low
Regime
Elevated / Watchful
Regime Assessment
Regime prints Elevated / Watchful with VIX at 15.91 - squarely in the watchful band, neither the low-vol carry paradise nor the panic zone that forces defensive posture. The half-life estimate of 15 sessions is the tell: this state has staying power, and mean-reversion mechanics won't rescue anyone who fades it too aggressively.
Transition math skews benign. Probability of escalation to panic over the next five sessions sits at 0.05 - low enough that tail hedges remain a cost, not a necessity. The ten-session probability of drifting back to the low-vol regime prints 0.45, meaningfully higher than the panic path. Directionally, the odds favor decay or drift-lower, not a break higher.
Translation for positioning: Elevated regimes reward patient premium sellers who respect the stickiness. Don't scale beyond standard sizing chasing the drift-lower thesis - the half-life cuts both ways, and being early to the low-vol pivot burns capital while the current state persists.
What it means for your trading
Regime is Elevated / Watchful at VIX 15.91 with a 15-session half-life - sticky enough to trust the carry, benign enough that panic-probability of 0.05 keeps tail hedges optional. Play for drift, not for the reversal.
Trading readVIX down, VVIX up, SKEW elevated, MOVE up - the price signals are diverging from the vol-of-vol signals. Divergences like this often precede regime shifts within 5-10 sessions.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve prints a textbook Contango shape: VIX9D at 14.33 sits well beneath spot VIX at 16.09, while VIX3M at 18.33 and VIX6M at 20.56 price meaningful forward event risk. The near slope of 12.28%% is the green light - carry is paying, and the curve is telling you the market fears the next two months more than the next two weeks.
Trade the slope, not the level. Sell front-end vol and roll into the 21-30 DTE window where the term structure pays the most per unit of tail risk. Calendars long the back month against a short front leg monetize the steepness directly; naked front-month shorts leave carry on the table.
What it means for your trading
Steep Contango with front-end suppressed and 3M/6M elevated favors vol sellers - harvest the roll-down in 21-30 DTE rather than fading the outright level.
Trading readSteep contango is a green light for vol sellers - carry is meaningfully positive across the 30-90 day window. But respect that steep contango is often the market's way of saying 'right now looks calm, don't extrapolate.'Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
ATM implied at 10.8% trades meaningfully rich to trailing HV20 at 7.18, printing a live VRP of 3.62%. The spread is active and paying - options are cheap-to-carry against what the tape has actually delivered over the last month, and the vol seller gets the classic setup where realized has decayed faster than implied has re-priced.
The catch sits one window back: HV60 at 12.84 runs well above HV20, meaning the older realized regime is materially hotter than the recent calm. Options are cheap-to-carry, but they are not cheap-to-hedge if the prior state reasserts. That gap is the risk premium's justification, not a mispricing.
Trade the front-window carry, respect the back-window memory. Sell premium into the VRP with defined wings - this is a monetize-the-decay setup, not a naked-vega one. Watch intraday ranges: any expansion that pulls HV20 toward HV60 flips the carry math and demands trimming before the print catches up.
What it means for your trading
VRP at 3.62% with IV at 10.8% over HV20 at 7.18 is a green light for premium sellers, but HV60 at 12.84 means the wing stays on - carry the trade, don't naked it.
Skew Convexity
The downside is where the premium lives. Quarter-delta puts print at 14.42% against an ATM anchor of 13.23%, driving the skew reading to -127.87% - a decisively negative tilt that says fear is being funded through the wings, not the body. Call-side risk reversals at 142.29% tell the mirror-image story: upside is a bid nobody is paying for.
The smile ratio at 0.1% confirms puts are structurally rich versus calls, but critically the ten-delta tail isn't screaming - this is priced fear, not priced panic. That distinction matters for structure selection.
Lean into the skew, don't fight it. Naked puts overpay for the very insurance the market is bidding up; put spreads monetize the steep near-strike richness while capping the wing you're short. On the upside, flat call skew makes short call spreads a clean way to harvest premium with no directional conviction required. The regime signature is Skew Steep - trade it accordingly.
What it means for your trading
Skew is meaningfully negative at -127.87% with a smile ratio of 0.1%, favoring spread structures over naked wings on both sides of the book.
Vol-of-Vol Structure
VVIX prints 89.94 against VIX at 15.91, pinning the ratio at 5.65 - a Low reading on the surface. But the tape underneath is louder: VVIX tacked on 4.23% today while spot vol bled lower. That is not a stable short-vol regime - that is the convexity market quietly re-pricing while the front end sleeps.
Historically this divergence - VVIX bid, VIX offered - is the signature that precedes short-vol shakeouts. The carry trade still works; the term structure at Contango confirms sellers get paid. But this is not the tape to press. Vol-of-vol is the second derivative and it's telling you the surface is more fragile than the print suggests.
Sizing: Standard Size. Do not scale up until VVIX stabilizes and the ratio compresses. If VVIX pushes higher while VIX stays offered, cut premium-short exposure before the convexity unwind drags the front end with it.
What it means for your trading
VVIX at 89.94 reads Low, but the intraday build against a softer VIX warns the convexity bid is early - respect Standard Size and resist upsizing short vol here.
Dispersion Spread
Index vol is sitting moderate with SPY ATM IV at 10.8%, but the story is underneath the surface - cross-strike IV dispersion at 85.02 confirms the risk has migrated to single names, not the index. AAPL, NVDA, and MSFT are all rebuilding positive gamma today, absorbing the dealer flow that would otherwise show up as index turbulence.
The read is clean: sell index vol, respect single-name vol. SPY/SPX premium is the cleaner short because the dispersion is doing the work of suppressing index realized while the mega-cap movers eat the variance individually. Index hedges will under-deliver here - a portfolio actually exposed to AAPL/NVDA/MSFT idiosyncratic risk needs single-name structures, not an SPY put spread that pays off only if the whole complex breaks together.
Bottom line: dispersion is Moderate and favors index premium sellers; the tape is telling you where the vol actually lives.
What it means for your trading
Index vol at 10.8% with cross-strike dispersion at 85.02 - sell SPY/SPX premium, don't confuse index calm for single-name calm as AAPL/NVDA/MSFT absorb the gamma.
Liquidity & Microstructure
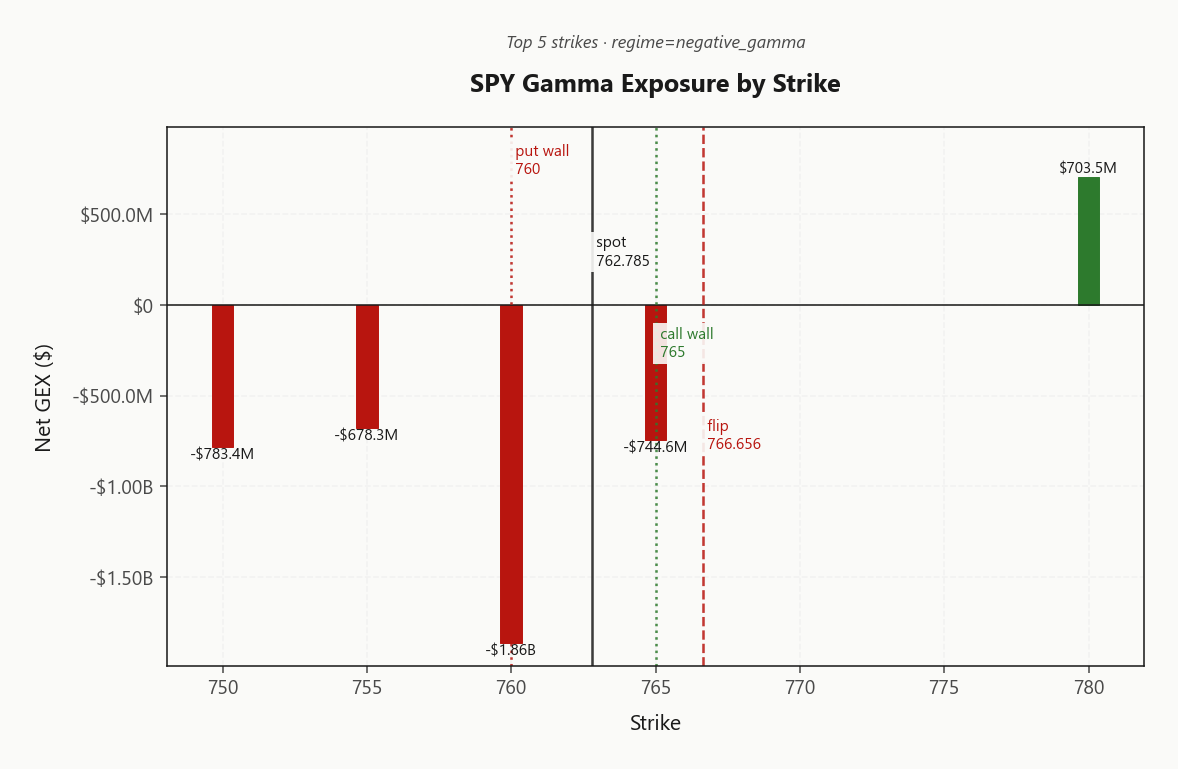
The book's headline OI sits at 525, but that print is a legacy hedge - miles from spot and irrelevant to today's dealer flow. The active cluster has migrated to 760.00, carrying -$1.86B of concentrated negative gamma. That is the magnet, the pressure point, and the accelerant all at once.
With spot pinned below the 766.66 flip, dealers are structurally short gamma through this zone - every tick lower forces more delta selling, every rally forces chase. The 765.00 call wall caps any upside squeeze; the 760.00 put wall is the pain floor where hedging demand thickens. Between them, price does not mean-revert - it amplifies.
The trade-relevant level is the top-strike cluster itself. Hold it and dealers stay pinned in the amplification band with intraday chop dominant. Break it and the negative GEX pocket below opens the trap door: forced selling cascades into the put wall with no dealer bid to catch it.
What it means for your trading
Ignore the legacy 525 print - the fight is at 760.00, where breakdown flips dealer amplification into a run at 760.00.
Trading readNegative gamma stacked below spot with the heaviest cluster at the top-strike zone means dealers sell into weakness - expect trend continuation on breakdowns, not the mean-reversion that a positive-gamma regime would deliver. The call wall above is where dealer flow flips supportive; a reclaim changes the entire intraday character.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Dealer greeks are stacked hostile. Net vanna at -$101.4B means any lift in implied vol forces dealers to sell delta into the move - the classic accelerant that turns a routine repricing into a cascade. Layered on top, charm at -$134.6K bleeds dealers shorter into every session close, a slow but relentless supply drip that gets worse as theta compresses.
The pivot to watch is the Call Wall at 765. Current bias reads Neutral, but that label is doing heavy lifting - below the pivot, vanna and charm both cut the same direction and dealer flow is a headwind. Reclaim it and the sign of dealer hedging flips supportive, which is when the tape stops fighting itself.
Trade the alignment, don't fade it: keep vol-spike hedges cheap while spot sits under the pivot, and treat any test of 765 as the binary - reclaim resets the regime, rejection hands the tape back to the vanna cascade.
What it means for your trading
Vanna and charm are pointing the same bearish direction with dealers structurally short into the close; the Call Wall at 765 is the single level that inverts that flow.
Cross-Asset Confirmation
Cross-asset tape reads Aligned and quietly defensive. MOVE at 77.88 is up 3.39%% on the session - rates vol is repricing under the surface, and that repricing typically bleeds into equity vol within a handful of sessions. Watch it as the leading tell, not the confirmation.
The sentiment tape is the contrarian counterweight. Fear & Greed prints Fear at 31 with indices camped near highs - sentiment cold, price warm. Historically this configuration pays premium sellers, not chasers of downside.
Across cap tiers the regime is uniform: SPY, QQQ at 706.88, and IWM at 292.73 all sit in negative gamma below their respective flips. Broad-based dealer defensiveness with no divergence yet - cross-asset tone reads Unknown. When everything aligns like this, the trade is watching for which index breaks the pattern first; IWM is the historical fragile link.
What it means for your trading
Rates vol at 77.88 is the early warning while sentiment at Fear is the contrarian tailwind - the setup favors disciplined premium sellers, not directional bears. Full Aligned regime across SPY/QQQ/IWM means the first index to diverge sets the next tape.
Scenario EV
The structure grid triangulates cleanly: with VRP active, VVIX contained but drifting higher, and the VIX curve locked in Steep Contango, the Short Put Spread prints the top score at 51. That's the trade the surface is paying you to put on - skew tilt does the work that a symmetric wing can't.
The iron condor lands at 48, close enough to tempt but wing-symmetric in a market where puts are meaningfully richer than calls. You give up the skew monetization for balanced tail coverage - a fair trade in a positive-gamma regime, a bad one here. Sweet spot sits in the 21-30 DTE window where the term-structure slope pays and the long wing keeps the tail contained.
Sizing stays standard per the VVIX guidance - do not scale up below the 766.66 flip. One gap through 760.00 on a VVIX bid triggers the vanna cascade, and that's the scenario the wing exists for.
What it means for your trading
Sell Short Put Spread in the 21-30 DTE window at standard size - the skew tilt edges out the iron condor's symmetric wing, and staying below the flip means respecting size, not chasing it.
Actionable Summary
Trade: sell Short Put Spread in the 21-30 DTE window, struck below the 760.00 put wall. VRP is active, VIX curve in Contango, and VVIX at 89.94 stays contained - the slope pays and the wing controls the tail.
Watch: the charm pivot at 765. Spot sits below the 766.66 flip in Negative Gamma territory; a reclaim of the pivot flips dealer flow from amplifying to supportive and changes the intraday character entirely. Until then, respect that vanna at -$101.4B makes any vol spike self-reinforcing.
Avoid: naked long premium into rich IV, oversized short strangles, and chasing breakouts through the 765.00 call wall without confirmation. Context:Elevated / Watchful regime with a 15-session half-life - sticky, do not fade the curve. Stop: a gap through 760.00 on rising VVIX = exit.
What it means for your trading
Sell Short Put Spread in 21-30 DTE below the 760.00 put wall while the Elevated / Watchful regime and Contango curve stay intact. Reclaim of 765 is the tell that dealer flow flips supportive; a gap through the put wall on rising VVIX is the exit.
Apple's inverse correlation to Mag7 for the first time in 20 years matters because it signals sector leadership rotation - index vol suppression can persist while single-name dispersion widens, which is exactly what dispersion-spread trades exploit.
CNBC's 'more cash than at any time this year' commentary is a sentiment tell - when established voices raise cash near highs with Fear & Greed already in fear, contrarian premium sellers get paid.
Exit from data center stock signals the AI trade is fatiguing at the edges - watch for GEX rebuilds in AI names (NVDA already showing this) as forced deleveraging resets positioning.
10-year yield at highest since Jan 2025 with Middle East tensions is the macro backdrop behind rising MOVE - rates vol leaking into equity vol is the transmission channel to watch.
Anthropic's $35B Lambda deal plus prior $50B and $45B commitments reveals mega-cap AI capex intensity - this is what sustains the AI GEX flow, and any hiccup in these deals would show up in single-name vol first.
Oil extending on Hormuz risk is the geopolitical wildcard - historically these shocks mean-revert but they inject tail risk into the vol surface (part of why 3M+ VIX is elevated).
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.91 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 766.66 against a spot of 762.79. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 10.8% with a volatility risk premium of 3.62%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.91. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime