Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 764.85 in Negative Gamma - net GEX -$1.94B with dealers positioned to amplify directional moves. Key levels: gamma flip at 766.47 (spot just below = fragile), call wall 765.00, put wall 760.00, highest OI cluster at 525. Dealer net DEX $29.86B with negative net VEX -$121.72B means vanna is hostile - a vol pop sells dealer delta and accelerates downside. VIX at 15.46 with Contango term structure (12.77 / 15.35 / 17.87 / 20.22) and VVIX at 88.02 - carry available, vol-of-vol contained. VRP at 2.8% with IV over 20d RV of 7.39; options rich to realized. Bottom line: sell Short Put Spread in the 21-30 DTE sweet spot, defend the 766.47 flip, cut size if spot breaks 760.00.
Negative gamma across index complex with Contango VIX curve - dealers amplify moves, vol sellers still paid
SPY at 764.85 sits just below the 766.47 gamma flip with dealers in Negative Gamma - every tick gets amplified by hedging flow. The Contango VIX curve and contained 88.02 VVIX say vol sellers are still paid, but the 765.00 call wall / 760.00 put wall corridor is where the tape lives today. Cross-asset regimes are aligned negative - no divergence yet, but any break of the flip changes everything.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
764.85
766.47
-0.21%
765
760
756
-$1.94B
Short gamma
QQQ
708.33
714.03
-0.80%
710
700
704
-$3.16B
Short gamma
IWM
292.89
297.90
-1.68%
300
290
290
-$4.14B
Short gamma
VIX
15.46
15.31
+0.98%
20
15
20
$805.47K
Long gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
10.19
7.39
+2.80
-142.55
2.55
1.30
QQQ
14.54
12.85
+1.69
-156.19
1.36
1.44
IWM
14.69
12.41
+2.28
2.44
2.59
2.31
VIX
75.92
75.39
+0.53
-114.90
0.38
0.32
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
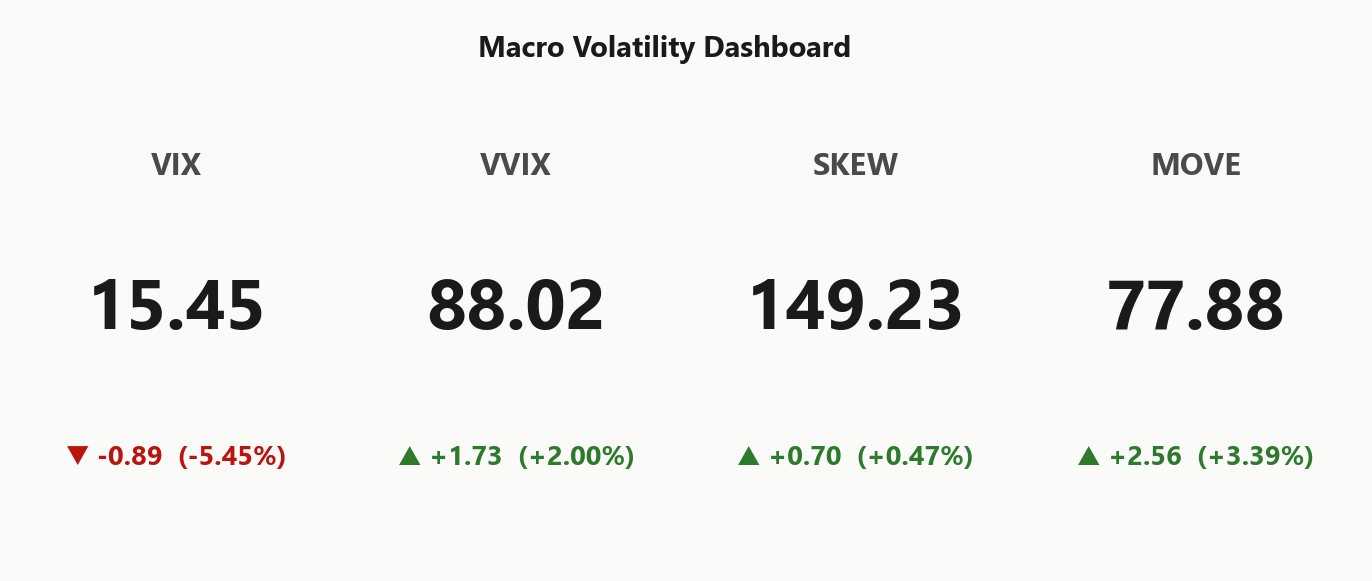
VIX
15.45
-5.45%
VVIX
88.02
+2.00%
SPX
7,665.06
+0.44%
SKEW index
149.23
+0.47%
MOVE (bond vol)
77.88
+3.39%
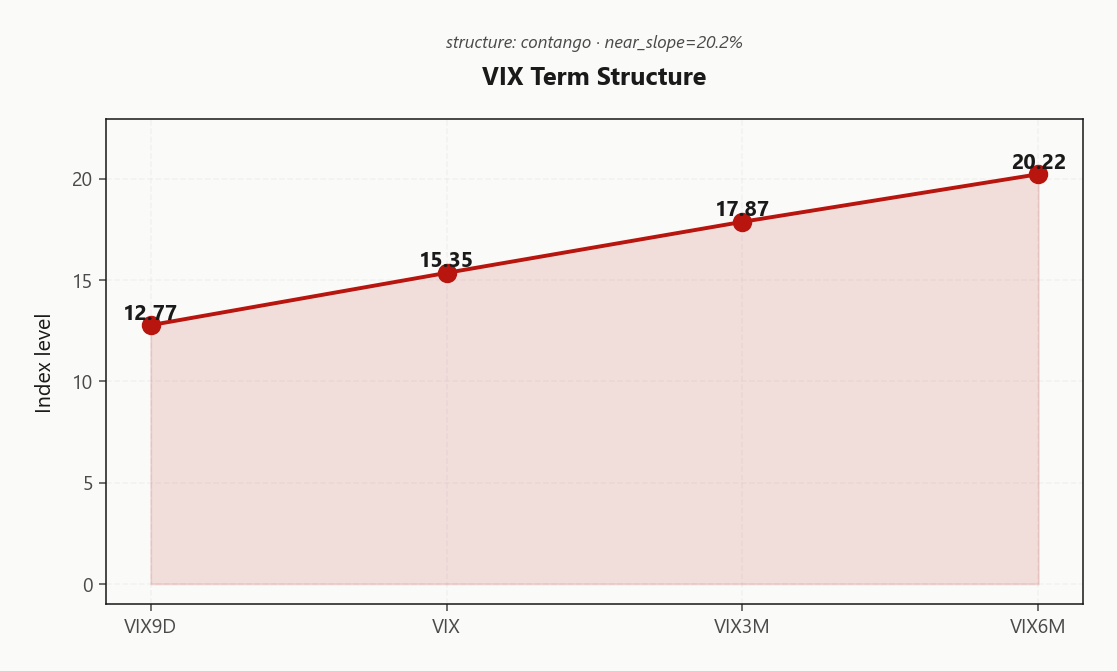
VIX term (9d/30d/3m/6m)
12.77 / 15.35 / 17.87 / 20.22
Steep contango
VVIX / VIX
5.70
Low
Regime
Elevated / Watchful
Regime Assessment
Regime reads Elevated / Watchful with VIX anchored at 15.45 - the sticky middle where vol is neither cheap enough to hoard nor rich enough to press without discipline. Half-life clocks at 15 sessions, which is the tell: this state persists long enough to bleed premium sellers who overstay, but not so long that you can treat carry as permanent.
Transition probabilities are asymmetric and that's the whole trade. Panic-regime odds over the next five sessions sit at 0.05 - negligible, no near-term shock priced. But drift-lower to the low-vol regime over ten sessions runs 0.45, materially higher. Path of least resistance is grind-tighter, not crack-wider.
Play it accordingly: harvest the Elevated premium while it's there, but don't overstay the half-life and don't get caught structurally short vol into the tail - regime transitions from here are one-way when they hit.
What it means for your trading
Elevated/Watchful is the carry regime with a clock on it - sell the premium, respect the 15-session half-life, and know that the asymmetric drift is toward lower vol, not panic.
Trading readVIX cooling while MOVE ticks up and SKEW stays elevated is the classic quiet-divergence setup - equity vol is complacent while rates and tail-hedgers say otherwise. When these reconcile, it's usually equity that moves.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
The VIX curve sits in Contango with the front end at 12.77 trading meaningfully cheap to spot 15.35 - the classic Steep Contango shape that pays sellers to be patient. The long tail stays bid, with 17.87 rolling into 20.22, keeping the term premium anchored and giving calendar structures a real slope to lean on.
Forward 30-to-60 prices at 19.0051072083, and that is the fat middle of the curve - the richest bucket to sell against a cheaper front. Steep contango - vol sellers favored is the regime label, and the read is unambiguous: short-vol carry and calendar spreads are structurally favored here, with the forward point doing the heavy lifting on decay.
The tell to watch is any flattening between 12.77 and 15.35 - that is where Steep Contango cracks first and the carry trade loses its cushion.
Trading readSteep contango - the vol carry trade is fully open and the market is not pricing near-term stress. Slope pays sellers, but the shape is a coiled spring if a shock hits the front.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
ATM IV prints 10.19% against a 20-day realized of 7.39 - options are meaningfully rich to the tape the market actually delivered. The 2.8% vol-point premium is real, concentrated at the 30-day tenor where sellers get paid cleanly. 60-day realized at 12.87 tells you what the last cycle of macro noise left on the tape - the near-term calm is a genuine compression, not a measurement artifact.
The caveat is regime, not price. With SPY in Negative Gamma and spot pressed against the 766.47 flip, realized can close the gap to implied in a single session if dealer amplification kicks in. Harvest the premium in structure - short put spreads under 760.00, not naked short vol - and treat the flip as the line where the VRP thesis converts from carry to catch-a-knife.
What it means for your trading
IV at 10.19% over realized of 7.39 is a clean 2.8% vol-point premium to sell, but negative gamma means the harvest must be structured - spreads over naked, and cut if the flip breaks.
Skew Convexity
Quarter-delta skew prints -142.55% with a smile ratio of 0.09% - puts remain bid harder than calls, but the surface is ordered, not panicked. Front-expiry 2026-09-03 put wing marks 13.94% against an ATM of 12.74%, a meaningful premium that pays you to spread rather than own outright convexity.
The call wing at 156.49% tells the second half of the story: zero upside conviction is being compensated. Nobody is reaching for topside gamma, so call skew stays flat while the put side does the work of pricing the negative-gamma tape below the 766.47 flip. That asymmetry - bid puts, flat calls - is the surface signature of a market that wants protection but refuses to chase.
Actionable read: fund downside hedges by selling the wing, not owning it. Put spreads harvest the elevated 13.94% wing against a richer ATM, aligning with the recommended Short Put Spread structure in the 21-30 DTE window. Naked long puts overpay for skew that is already priced.
What it means for your trading
Skew is steep-but-ordered: quarter-delta at -142.55% with put wing IV 13.94% rewards spread structures over outright puts, while flat call skew confirms no one is paying for upside convexity.
Vol-of-Vol Structure
VVIX at 88.02 against VIX at 15.45 prints a ratio of 5.70 - squarely in Low vol-of-vol territory. The market is not pricing a bimodal jump, and the wings aren't bidding for convexity the way they would if a shock were being seriously discounted. That gives short-vol structures room to breathe.
Sizing guidance reads Standard Size - no need to half-size the book here. Low VVIX is a green light for carrying the recommended Short Put Spread at full weight, provided you respect the 766.47 flip and the 760.00 put wall as the risk-off triggers.
Watch the VVIX tape closely: today's tick of 1.73 against a cooling VIX is the divergence to flag. Vol-of-vol drifting up while spot-vol softens is how the market quietly re-prices tail risk before the equity complex catches on. No jump premium being aggressively bid yet - but that's the signal that turns first.
What it means for your trading
VVIX at 88.02 vs VIX 15.45 keeps vol-of-vol Low - carry short-vol structures at Standard Size, but flag any VVIX/VIX divergence as the leading tell that the regime is about to re-price.
Dispersion Spread
Index ATM IV sits at 10.19% with cross-strike dispersion at 67.53 - a moderate-correlation print that tells you the index is doing the work while single-name premium is not paying you enough for the idio tail you're absorbing. Cross-expiry dispersion at 2.86 is a modest term-structure spread, consistent with the steep-contango backdrop but nothing exotic in the belly.
The tech premium is visible where it should be: QQQ ATM at 14.54% against SPY at 10.19% reflects the AI-basket beta rather than genuine dispersion opportunity - you're paying up for correlated names, not diversifiable variance. In this regime, harvest vol at the index level where liquidity, VRP, and dealer-flow visibility all favor you; single-name shorts leave the idiosyncratic tail uncovered by the index hedge.
What it means for your trading
Moderate correlation with cross-strike dispersion at 67.53 - sell index vol, don't reach into single names where the premium doesn't compensate the idio risk.
Liquidity & Microstructure
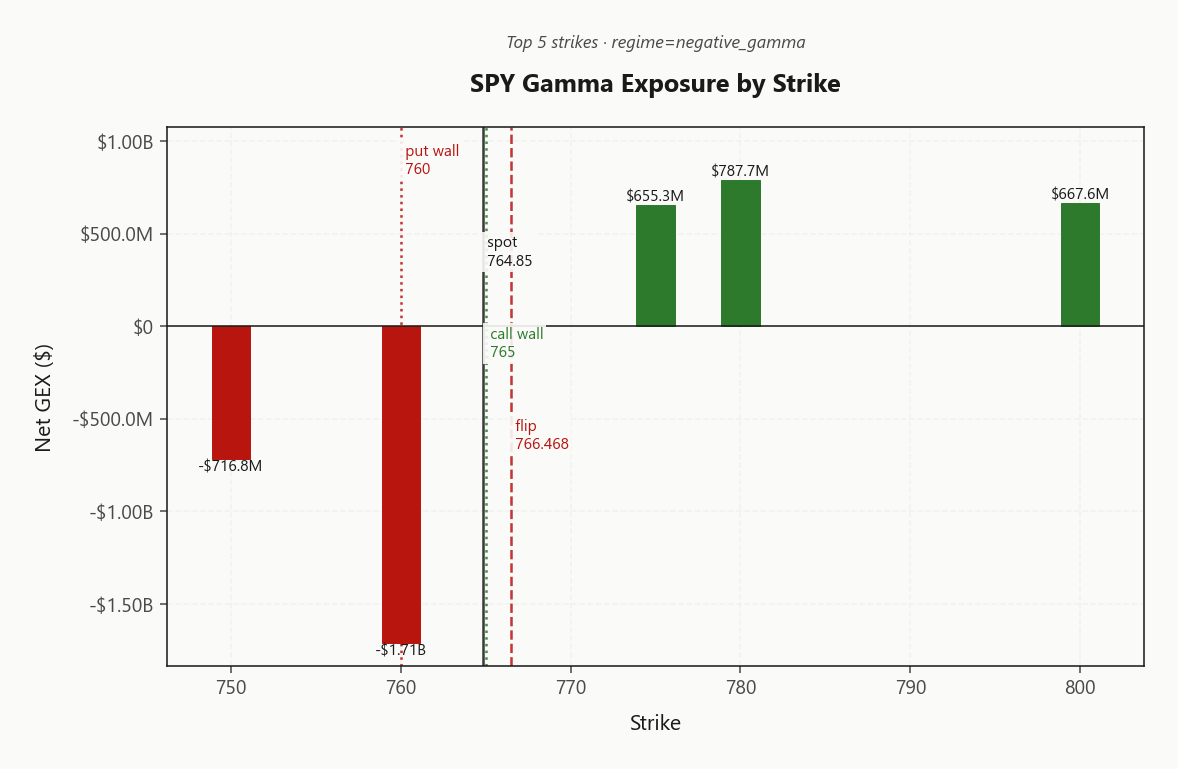
The book pivots on 766.47 with spot at 764.85 sitting just below - a fragile perch where dealer hedging flips from stabilizing to amplifying on any tick lower. The 765.00 call wall caps upside chases and pulls rallies back into the corridor, while 760.00 is where dealer sell-flow accelerates on a break.
Open interest concentrates at 525, but the live gravity is at 760.00, where 293466 contracts anchor -$1.71B of dealer gamma - a magnet on quiet tape, an accelerant if it fails. Trade the range, fade the extremes, and respect the flip as the regime switch.
What it means for your trading
Above 766.47 the tape mean-reverts inside the 760.00 - 765.00 corridor; below it, dealer amplification takes over and the top-strike cluster at 760.00 becomes the sell-flow trigger.
Trading readDealers short gamma right around spot with a heavy negative cluster near 760.00 - every downside tick sells dealer stock into it, while the 765.00 shelf caps upside chases. Trade the range, fade the extremes, respect the flip.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Dealer greeks are stacked on the accelerant side. Net VEX prints at -$121.72B - decisively negative - which means Vol up = dealers sell delta - downside amplified if vol spikes. Any vol repricing higher forces the desk to shed delta into weakness, not absorb it. Net CHEX at -$2.7M layers charm decay on top: time is not a stabilizer here, it's a directional current.
The charm pivot sits at 765 - the Call Wall - with spot practically welded to it at a distance of 0.0196116886. Current bias reads Neutral, which in this greek configuration translates to coiled, not calm. Above the pivot, charm drains delta out of the call wall and dealers lean harder against the shelf; below it, hostile vanna takes the wheel and downside gets multiplied through the hedge book.
Trade the pivot as the flow line, not a target. Reclaim and hold above 765 keeps the amplification benign; loss of the flip with any VIX tick puts the vanna accelerant live and rewards structures already short delta.
What it means for your trading
Negative VEX plus negative CHEX with spot pinned on the Call Wall charm pivot at 765 is the textbook accelerant setup - a vol pop sells dealer delta and downside compounds. Defend the pivot; don't fade a break of it.
Cross-Asset Confirmation
The cross-asset tape is telling on itself. MOVE prints 77.88 (3.39%) while VIX cools to 15.45 - rates vol quietly bid, equity vol softening. That's the classic quiet-divergence: fixed income desks are paying up for gamma while equity vol sellers get comfortable. When these two reconcile, it's almost always equity that closes the gap.
SKEW at 149.23 corroborates - tail-hedging demand persists even as ATM bleeds. Meanwhile Fear & Greed reads Fear at 34 despite the bid tape, a contrarian setup where positioning is defensive into a grind higher. Sentiment fades usually pay near-term, but the wing bid says the smart-money hedge is still on.
Regime read across the complex is Aligned with QQQ at 708.33 and IWM at 292.89 both parked in negative gamma alongside SPY. No cross-asset shock absorber - small caps and tech will follow index beta-plus into any break. First name to reclaim its flip is the leadership tell.
What it means for your trading
Rates vol bid, equity vol soft, tail-hedgers still paying up, sentiment defensive - the setup rewards short-vol carry today but the divergence between MOVE at 77.88 and VIX at 15.45 is the tell that this regime cracks from the rates side, not the equity side. Watch the first index to reclaim positive gamma for the all-clear.
Scenario EV
The scorecard prints Short Put Spread at 48 versus the iron condor at 47 - a narrow beat, but the tiebreaker is directional put-side skew. Symmetric premium collection leaves money on the table when the wing is bid this hard; the structure that leans into the paid side of the smile wins on both expected value and hedging cost.
Live the trade in the 21-30 DTE bucket. That window sits past front-week gamma decay - where negative-gamma whip risk is most acute - and stops short of the next macro event horizon, so theta compounds without stapling you to a catalyst. Anchor the short strike below the 760.00 put wall so dealer support sits between spot and your break-even, not the other way around.
Sizing gets the green light: VVIX reads Low, guidance is Standard Size. No jump-risk premium is being aggressively bid, so half-sizing forfeits carry for no measurable convexity gain. Full clip, defined risk, wing-aware.
What it means for your trading
Sell Short Put Spread in 21-30 DTE below the 760.00 put wall - the score edge is thin but the skew geometry and Low vol-of-vol make it the cleanest VRP harvest on the board at Standard Size.
Actionable Summary
Trade: sell Short Put Spread in the 21-30 DTE bucket, structured below the 760.00 put wall for cushion. VRP is live, skew is steep-but-ordered, and the put-side edge beats the condor on score - take the directional carry, not the neutral one.
Levels: defend the 765Call Wall as the flow-direction line, with the gamma flip at 766.47 as the regime switch. Spot sits just below the flip in Negative Gamma - dealers amplify every tick until reclaimed. Avoid naked upside calls (call skew is flat, no one's paying for chase) and long premium into Contango.
Size & watch: regime reads Elevated / Watchful with VVIX Low - go Standard Size, no need to half-size. Cut aggressively if 760.00 breaks. Quiet warning: 77.88 MOVE ticking up while VIX cools to 15.45 - rates vol is the tell for when this regime cracks.
Broadcom earnings + NVDA relative strength is the single biggest catalyst risk in tech complex right now - AVGO print will re-rack dealer gamma across the AI basket into tomorrow's open
AAPL inversely correlated to tech peers for the first time in 20 years is a structural positioning story - explains why the mover GEX shift is idio, not beta
Cramer signaling largest cash position of the year confirms the defensive-sentiment reading in Fear & Greed and the contained VVIX - smart-money is de-risking without panic
10-year yield at highest since Jan 2025 with MOVE ticking up while VIX cools = the rates-vol divergence that eventually pulls equity vol higher, and the tell for when this regime cracks
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.46 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 766.47 against a spot of 764.85. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 10.19% with a volatility risk premium of 2.8%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.45. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime