Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
Market Overview
Data-driven market structure analysis powered by lab.flashalpha.com - volatility, dealer positioning, and regime assessment across the index complex, refreshed multiple times per trading day. Every number is pulled straight from our API endpoints by deterministic code.
FlashAlpha ResearchAI-assisted
Generated
Validated citations - no literal numbers from LLM
You're reading yesterday's market analysis
Basic unlocks today's post-open analysis (9:45 ET).
Growth unlocks all 3 daily refreshes (open, midday, close) plus actionable trade ideas and “What it means for your trading”.
Growth unlocks the full trading day: midday (12:30 ET) + close wrap (4:15 ET), actionable trade ideas per section, and “What it means for your trading” analysis.
SPY at 765.40 is glued to the 765.00 put wall with dealers net short gamma (-$3.27B) - the 767.73 flip sits just above spot, so we're in an amplification regime until a breakout reclaims it. Key levels: call wall 770.00, put wall 765.00, max pain 755.00 - spot pinned right at the put shelf means any downside break has no dealer cushion until the next OI zone. Dealer vanna is negative (-$127.29B) and charm is bleeding sell pressure (-$503.5K) - a VIX pop from here forces dealers to sell more delta, compounding downside. Vol read: VIX 15.23, VIX9D/3M term structure in Contango at 20.87%% slope, ATM IV 9.99% vs 20d RV 7.36 = VRP of 2.63% still paid to sellers. VVIX at 86.64 is benign - jump risk is not being priced aggressively despite negative gamma. Fear & Greed at 34 (Fear) - retail already positioned defensively, tactical bounces possible off 765.00. Bottom line: sell 21-30 DTE Short Put Spread structures above the 767.73 flip, cut/flip if spot loses 765.00 on volume.
Negative gamma across index complex, VIX in contango - dealers amplify moves but vol sellers still favored
SPY at 765.40 is sitting directly on the 765.00 put wall with dealers short gamma across SPY, QQQ, and IWM - any downside break amplifies while any relief pop meets the 770.00 call wall. VIX at 15.23 with a steep contango term structure (20.87%% slope) says the market is paying carry for vol sellers, but VVIX at 86.64 keeps sizing modest. Fear & Greed at 34 (Fear) plus negative dealer vanna means a vol pop from here compounds downside - respect the flip at 767.73.
Dealer positioning levels
Symbol
Spot
Gamma flip
vs Flip
Call wall
Put wall
Max pain
Net GEX
Regime
SPY
765.40
767.73
-0.30%
770
765
755
-$3.27B
Short gamma
QQQ
709.37
716.53
-1.00%
715
700
704
-$2.80B
Short gamma
IWM
293.97
298.59
-1.55%
300
290
290
-$3.95B
Short gamma
VIX
15.23
15.23
+0.01%
20
15
20
$4.20M
Long gamma
Spot below the gamma flip means dealers are short gamma and hedge with the move, which amplifies range. Above it they hedge against the move, which dampens it.
Volatility and risk premium
Symbol
ATM IV
HV 20d
VRP
25d skew
P/C OI
P/C volume
SPY
9.99
7.36
+2.63
-154.30
2.54
1.39
QQQ
14.43
12.87
+1.56
-154.11
1.36
1.48
IWM
14.27
12.75
+1.52
2.66
2.59
2.17
VIX
71.66
76.51
-4.85
-116.10
0.38
0.32
VRP is implied minus realised volatility. Positive means options are pricing more movement than has actually occurred, which favours sellers.
Volatility complex
Measure
Value
Change
VIX
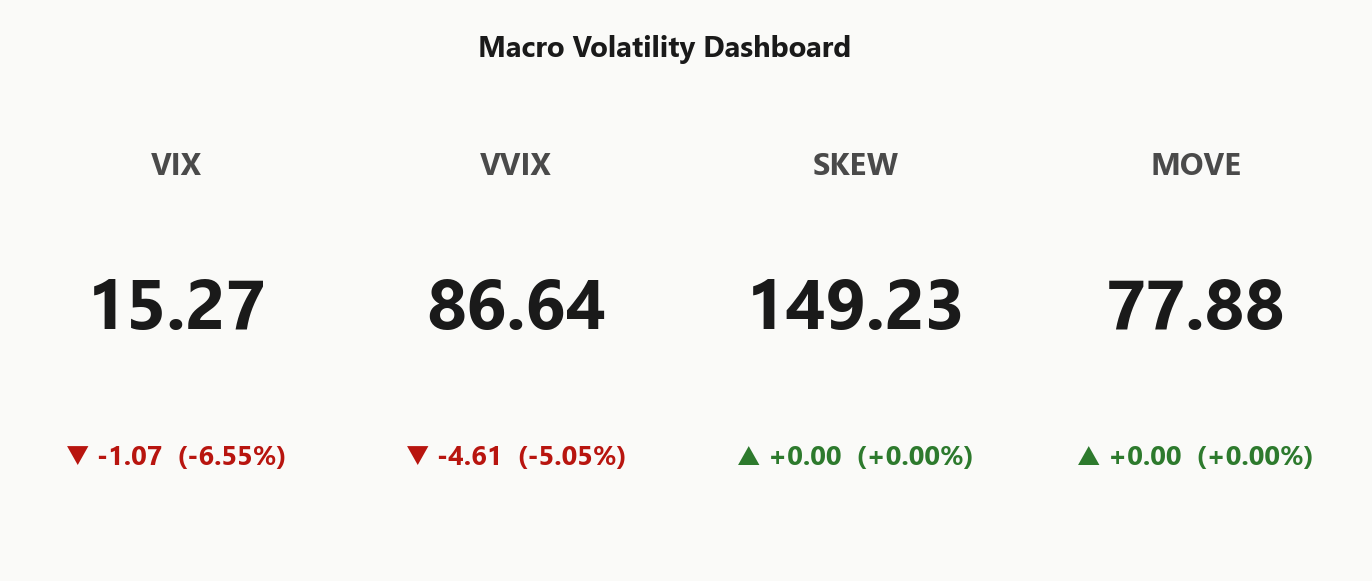
15.27
-6.55%
VVIX
86.64
-5.05%
SPX
7,666.60
+0.46%
SKEW index
149.23
0.00%
MOVE (bond vol)
77.88
0.00%
VIX term (9d/30d/3m/6m)
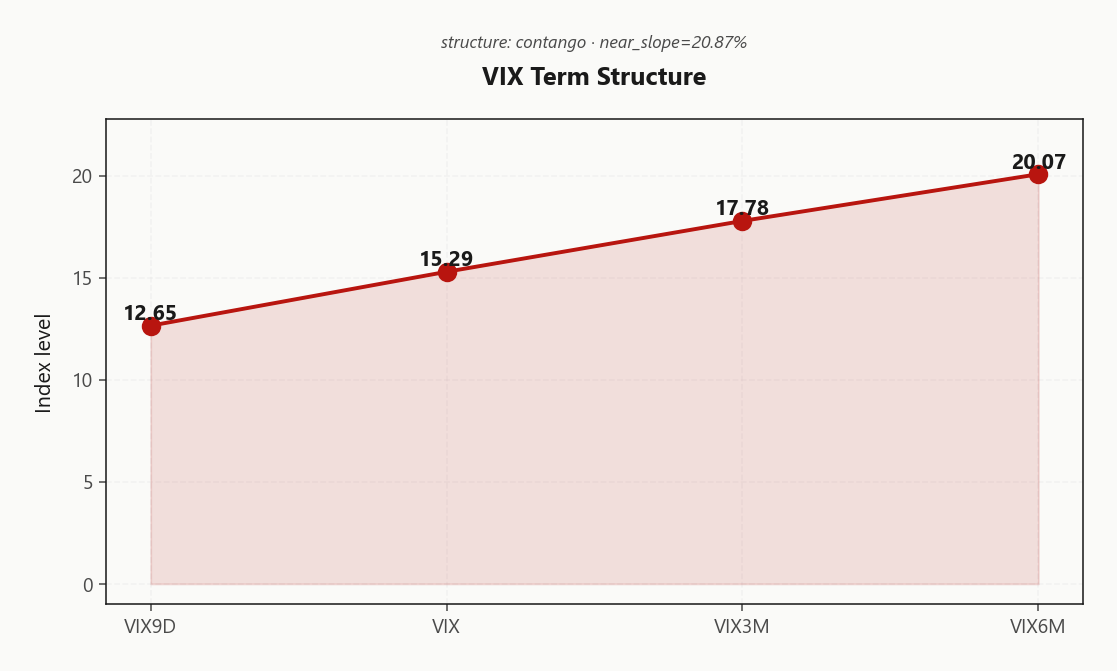
12.65 / 15.29 / 17.78 / 20.07
Steep contango
VVIX / VIX
5.67
Low
Regime
Elevated / Watchful
Regime Assessment
Current tape prints Elevated / Watchful with VIX anchored at 15.27 - a sticky middle-zone regime whose empirical half-life runs 15 sessions. That's the operative timeframe: this is not a state that resolves in a day, and forcing a directional thesis before the 767.73 flip is reclaimed pays out poorly.
Transition probabilities skew constructive at the tails - 0.45 drift back to low over ten sessions versus 0.05 escalation to panic in five. Translation: the modal path is grind lower in vol, not a jump. VVIX at 86.64 and MOVE at 77.88 corroborate - no cross-asset stress bid.
Trade the range: Short Put Spread in the 21-30 DTE bucket harvests the contango without pressing direction. Escalate defense only if spot loses 765.00 on volume - that's the regime-break trigger, not the tape drift.
What it means for your trading
Elevated but sticky - 15 session half-life with drift-to-low (0.45) materially more likely than panic escalation (0.05). Range-trade the regime; the flip at 767.73 is the arbiter of whether that thesis stays intact.
Trading readVIX 15.27 down, VVIX 86.64 down, MOVE 77.88 calm, SKEW 149.23 still elevated - everything confirming vol seller thesis except SKEW's persistent tail bid, which is the one quiet warning.VIX = equity vol. VVIX = vol of vol (is the fear gauge itself being stressed?). SKEW = cost of tail hedges vs ATM. MOVE = bond vol. Divergences between them (e.g. calm VIX but elevated VVIX) often precede regime shifts.
Forward Vol Geometry
Term structure is Contango and steep - VIX9D at 12.65 sits well beneath spot VIX 15.29, which in turn concedes to 3M at 17.78. The curve is paying carry the whole way out; no event premium is being marked into the belly.
Forward 18.9023953509 on the 30 - 60 leg and 22.1242265402 on the 60 - 90 extend the same message - the market is pricing continued roll-down, not a stress rerate. Regime tag reads Steep contango - vol sellers favored, and cross-asset alignment is Aligned, so there is no divergence in the vol complex to fade.
Trade the geometry, not the tape: the 21-30 DTE bucket is the sweet spot for harvesting the curve slope, even with dealers pinned in Negative Gamma. Vol sellers stay favored until the front reclaims the belly.
What it means for your trading
Steep Contango from 12.65 through 17.78 keeps the carry trade paid; forward vols on the 30 - 60 and 60 - 90 confirm no stress premium in the belly. Sell the 21-30 DTE roll-down while the curve holds shape.
Trading readSteep contango at 20.87%% front-slope with front-month future 17.78 well above spot - carry trade fully intact, no event premium priced beyond the belly.Forward VIX curve: VIX9D (9-day), VIX (30-day), VIX3M, VIX6M. Upward slope (contango) = calm regime + vol sellers favored. Downward (backwardation) = stress, vol buyers favored. Slope matters more than level.
Realized Vol Structure
Implied is sitting comfortably rich to the tape: ATM at 9.99% against 20-day realized of 7.36 leaves 2.63% points of VRP on the table - a Moderate Premium read that keeps premium sellers paid for the gap risk they're wearing.
The realized curve has decelerated - 5-day at 8.76 printing above 20-day 7.36, but both well inside the implied band. That's the shape that turns short-dated VRP into a real edge rather than an accounting mirage; the tape simply isn't delivering the vol the options are quoting.
Caveat holds: with dealers pinned in negative gamma at -$3.27B and spot glued to the 765.00 shelf, the VRP is earned income, not free money - any 765.00 break on volume forces dealer selling that can collapse the realized-implied wedge in a single session. Defined-risk over naked, always.
What it means for your trading
IV at 9.99% against 20d RV of 7.36 leaves 2.63% points of paid VRP - sell the premium in defined-risk structures, but respect that negative gamma below the 767.73 flip means the cushion vanishes fast if 765.00 breaks.
Skew Convexity
Front-week skew reads distorted: -154.3% on the quarter-delta measure with a smile ratio of 0.08% - the near expiry is pulling the surface around and the tape print is not the real signal. Strip the front weekly and the shape is orderly hedging, not a tail bid: put 13% against ATM 12.19% is a narrower spread than negative gamma alone would justify, meaning the downside wing is not being aggressively bid despite dealers short across the complex.
Call side offers no counter-signal - 167.3% shows zero upside chase, consistent with a market that is defensively positioned but not reaching for convexity in either direction. That is the trade tell: skew premium is present but paid down, so structure choice matters more than direction. Prefer put spreads over naked puts to sidestep the wing premium you would otherwise finance, and skip the ratio structures until the front-week roll clears and weekly skew prints clean.
What it means for your trading
Front-week noise aside, the quarter-delta shape at -154.3% with put IV of 13% vs ATM 12.19% reads as ordered hedging rather than a genuine tail bid. Sell verticals, not wings.
Vol-of-Vol Structure
VVIX at 86.64 against VIX 15.27 prints a ratio of 5.67 - squarely in Low territory. The vol-of-vol tape is not pricing jump risk, even with Fear & Greed reading Fear and dealers pinned short gamma across the index complex. Convexity buyers are absent.
That mismatch is the trade. Negative gamma says a spot break amplifies, but the VVIX/VIX ratio says nobody is paying up for the tail - the option on the option is cheap. Standard Size sizing is appropriate for premium sales here; there is no bimodal outcome embedded in the surface, no binary catalyst bid distorting the wings.
Read it as permission, not confirmation: harvest carry at standard clip, but respect that a VVIX rerate - not a VIX pop - is what would flip the sizing rule. Until then, the vol-of-vol channel stays the green light on the dashboard.
What it means for your trading
VVIX at 86.64 and a 5.67 ratio keep vol-of-vol in the Low zone - Standard Size for premium sales, with a VVIX rerate (not a VIX pop) as the trigger to cut.
Dispersion Spread
Index vol sits 9.99% ATM against QQQ at 14.43% - the tech-led risk premium is intact and dispersion is doing its job without going pathological. Cross-strike dispersion prints 77.59 with cross-expiry at 2.96, a smile that is functioning normally rather than fracturing - no single-name blow-out is being telegraphed through the index book.
With correlations sitting in the moderate zone and the complex synchronized (Aligned) in negative gamma, the cleanest expression is index vol selling over single-name. Selling SPY into the QQQ premium captures the tech risk load without eating the idiosyncratic tails; index hedges are the right instrument here, and single-name short-vol carries pay-off asymmetries the dispersion tape does not justify.
What it means for your trading
Moderate correlation with SPY IV at 9.99% below QQQ 14.43% and cross-strike dispersion 77.59 - sell index vol, hedge index, leave single-name premium to specialists.
Liquidity & Microstructure
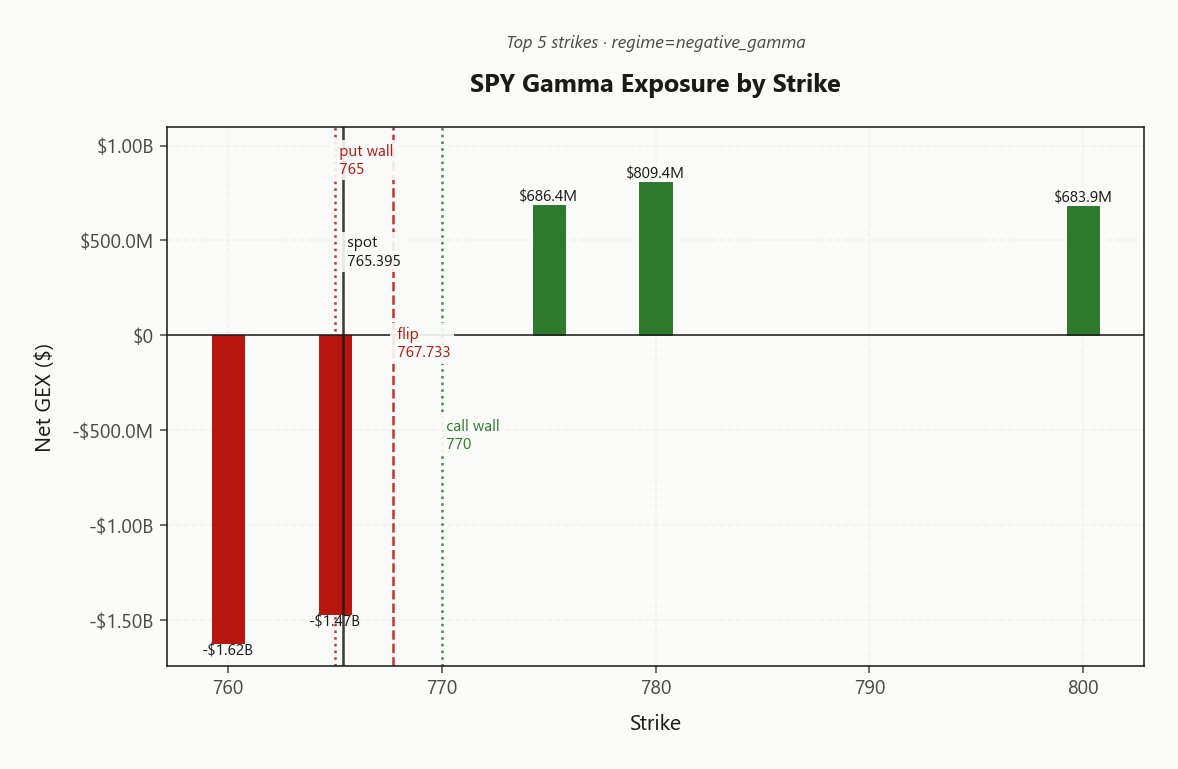
Open interest headline reads 525 as the highest OI strike, but that print is stale deep-ITM LEAPS carry - not the tape's battleground today. The live fight sits inside the 765.00 - 770.00 corridor, with the gamma flip at 767.73 functioning as the flow-regime switch. Spot at 765.40 is pinned fractionally beneath the flip, keeping dealers in amplification mode until it's reclaimed on volume.
The dominant shelf is 760.00, carrying -$1.62B of net GEX - a heavy put concentration that has anchored the tape into the close and defines the trapdoor. Lose it and there is no dealer cushion until the next OI zone; hold it and the mean-reversion bid rebuilds against the 770.00 cap.
Trade the level, not the noise: above 767.73 dealers cushion rallies and the book breathes; below, they sell into weakness and every tick compounds. The microstructure is deep but directionally hostile below the flip - respect it.
What it means for your trading
The tradable microstructure lives between 765.00 and 770.00, with 767.73 as the amplify/cushion pivot and the 760.00 put shelf as the trapdoor. Sub-flip spot means dealer flow works against dips until the flip is reclaimed.
Trading readMassive negative GEX cluster at the 765.00 - 767.73 zone with call resistance stacked at 770.00 - dealers amplify moves in either direction, mean-reversion breaks down until spot reclaims the flip.Net dealer gamma exposure at each strike. Green bars = dealers long gamma (dampens moves toward the strike), red bars = short gamma (amplifies moves). Lines show spot, gamma flip (regime boundary), and the highest-gamma call/put strikes (walls).
Dealer Vanna & Charm
Dealer vanna sits deeply negative at -$127.29B while charm bleeds negative at -$503.5K - a combination that turns any uptick in implied vol into mechanical delta selling, while time decay quietly leaks the same direction into the bell. Vol up = dealers sell delta - downside amplified if vol spikes - a VIX pop from here forces dealers shorter delta rather than cushioning the tape.
The charm pivot lands at 765 - a Put Wall level, and spot is sitting within -0.05160734 of it. Bias reads Neutral, which is exactly the knife-edge you'd expect with spot glued to a shelf that carries both structural OI and the charm inflection.
Vanna and charm are both pulling the same negative direction with spot pinned within -0.05160734 of the 765 pivot - a vol pop or a break of 765.00 converts dealer hedging into an accelerant, not a brake.
Cross-Asset Confirmation
Cross-asset tape is Unknown and this is not a rates or credit event - MOVE sits benign at 77.88, well inside recent ranges, while the vol shock lives entirely in equity dealer books. Fear & Greed at 34 (Fear) confirms an equity-isolated defensive posture: retail already leaning short, no cross-asset contagion bid.
SPY, QQQ at 709.37, and IWM at 293.97 are Aligned in negative gamma - synchronized pressure across the index complex with each name grinding into its own put shelf. No diversification available inside equity beta; the whole book is fragile on the same axis at the same time, with IWM the most convex to a real break.
Trade the equity-positioning story, not a macro shock. VIX sits in positive-gamma while stocks sit short - that asymmetry is what keeps vol sellers paid despite the negative-gamma tape underneath.
What it means for your trading
MOVE calm at 77.88 and Fear & Greed at Fear isolate the fragility to equity positioning, not credit or rates. With SPY, QQQ, and IWM Aligned in negative gamma, there is no cross-asset hedge inside the complex - size the risk accordingly.
Scenario EV
The scorecard tilts to Short Put Spread at 38, edging the iron condor at 36 - a directional-skew tilt beats pure premium collection when the tape is glued to the 765.00 shelf with dealers short gamma. VRP paid at 2.63% and VVIX benign at 86.64 means Standard Size works; no need to trim for jump risk that isn't priced.
Sweet spot sits in the 21-30 DTE bucket - long enough to harvest the full term-contango roll-down at 20.87% front-slope, short enough to sidestep the 17.78 future's belly if it repositions on a shutdown-vote miss. Structure short strikes below the 765.00 shelf, cap risk above the 767.73 flip.
Skip strangles and calendars until skew normalizes off the -154.3% print or VVIX rerates - front-week smile at 0.08% is distorted by expiry mechanics, and steep contango bleeds calendar theta faster than the belly can catch up.
What it means for your trading
Sell Short Put Spread in 21-30 DTE at Standard Size - directional-skew tilt scores 38 vs condor 36, and VRP plus benign vol-of-vol keeps the risk/reward paying. Avoid strangles and calendars until the skew or VVIX regime shifts.
Actionable Summary
Primary trade: sell Short Put Spread structures in the 21-30 DTE bucket with short strikes stacked below the 765.00 put wall, staying above the 765 pivot. Regime reads Elevated / Watchful - VRP is paid at 2.63%, VVIX at 86.64 keeps jump risk contained, and Standard Size is the right clip.
Avoid: naked short puts beneath the 767.73 flip and calendar spreads while the front slope holds 20.87% - the belly bleeds you either way. Watch: a break of 765.00 on real tape flips the book to defense; a reclaim of 770.00 is the green light to add.
Tag out weekly if VIX at 15.27 pops above the front-month future at 17.78 - that inversion is the tell the carry regime has cracked.
Apple's 20-year decorrelation from tech peers is a structural signal - mega-cap AI trade is no longer monolithic, changing how dealers hedge the QQQ complex.
Amazon FTC lawsuit sitting on top of the fifth-largest GEX mover means dealer books already carry event risk into a live legal catalyst - pin risk elevated.
AI token prices hitting record lows corroborates the AI-trade fatigue narrative that's showing up in Apple's decorrelation and defensive rotations - watch for continued mega-cap dispersion.
Well-followed portfolio exiting data-center exposure over AI concerns lines up with the negative-gamma tape and elevated fear reading - real-money positioning is turning defensive.
Government shutdown vote is a near-term tail catalyst - if it fails, front-week VIX repricing hits the steep contango and blows out the roll-down trade.
10-year yields at highest since Jan 2025 on Middle East tensions is the macro undertone MOVE isn't yet reflecting - watch rate vol as the sleeper risk into the close.
Frequently Asked Questions
What is the current market volatility regime?
VIX is trading at 15.23 with a Contango term structure. The Fear & Greed index reads Fear, and cross-asset volatility is Aligned across SPY, QQQ, and IWM.
SPY's gamma flip is at 767.73 against a spot of 765.40. Above flip, dealer hedging is suppressive; below it, hedging amplifies moves.
Is implied volatility rich or cheap versus realized?
SPY's at-the-money implied vol is 9.99% with a volatility risk premium of 2.63%. Negative VRP means options are cheap relative to recent realized moves; positive VRP means insurance is expensive.
What does the VIX term structure say today?
The VIX curve is in Contango with VIX at 15.27. Contango signals benign forward expectations; backwardation signals near-term stress.
You're reading yesterday's market overview. Upgrade to Basic and get today's post-open analysis - the same data institutional desks use to set positioning each morning.
Unlock the full trading day
You see the market-open report. Growth gives you all 3 daily refreshes - midday regime shifts, close-wrap positioning, plus actionable trade ideas and "What it means for your trading" analysis.
What Basic includes
Today's market-open analysis
SPY, QQQ, IWM, VIX gamma regime
Key levels - flip, walls, max pain
VIX term structure + VRP analysis
Charts with trading reads
Full API access to lab.flashalpha.com
What Growth adds
3x daily refreshes (open, midday, close)
Actionable trade ideas per section
"What it means for your trading"
Regime shift alerts intraday
Close-wrap end-of-day positioning
Full archive history access
Plans start at $63/mo (billed yearly) · Cancel anytime