Help us double down on what's working, instead of guessing. Takes 5 seconds, totally optional.
gammaexposure · 15 min read
What Is Gamma Exposure (GEX)? Dealer Hedging 101
Gamma exposure estimates the change in a modeled options book's dollar delta per 1% underlying move. Learn the units, dealer-sign assumptions, gamma flip and limitations with a saved replay example.
Gamma exposure (GEX) is a modeled change in dollar delta per specified underlying move. This guide reports dollars per 1% move. It requires assumptions about dealer positions; it does not observe actual dealer inventory or guarantee support, resistance or price direction.
What is gamma exposure (GEX)?
Gamma exposure (GEX) estimates the change in an options book's dollar delta for a specified underlying-price move. Here, GEX is expressed as dollars of delta notional per 1% underlying move. Dealer-position signs are inferred from a stated convention, so it is a model of possible hedging pressure, not a measurement of stock that every dealer must trade.
Markets sometimes range near an options concentration and sometimes break through it. Gamma provides one possible hedging mechanism to investigate. A chart pattern alone cannot identify which positions caused a price move.
Options-related hedging interacts with news, liquidity and other flows. Compare matched observations and state the assumptions before attributing a reversal or trend to dealer gamma.
The tool that maps those invisible forces is called gamma exposure, or GEX. If you trade stocks, ETFs, or options and you do not understand GEX, you are missing one of the most powerful inputs available to you.
This guide will explain gamma exposure from the ground up, no advanced math required to follow along, though we will include the formulas for those who want them.
What Is Gamma Exposure?
To understand gamma exposure, you need to understand two things first: delta and gamma. (If you want to calculate these yourself, try our free options Greeks calculator.)
Delta
Delta measures how much an option's price changes when the underlying stock moves by $1. A call option with a delta of 0.50 gains $0.50 when the stock rises by $1. Delta also approximates the probability that an option expires in-the-money.
Gamma
Gamma is the rate of change of delta. It tells you how much delta itself changes when the stock moves by $1. High gamma means delta is shifting rapidly, the option is becoming more or less sensitive to price changes very quickly.
Now, here is the important part. When you buy an option, someone sells it to you. That counterparty is almost always a market maker (also called a dealer). Dealers do not want to bet on direction, they want to collect the spread and stay neutral. To stay neutral, they must hedge their delta exposure by buying or selling the underlying stock.
Because gamma changes delta, dealers have to constantly adjust their hedges as the stock price moves. Gamma exposure aggregates all of this hedging pressure across every open option on a stock or index.
Gamma Exposure (GEX)
The modeled dollar-delta sensitivity of the included options per 1% underlying move. Positive and negative signs describe the assumed position book; the resulting hedge behavior remains conditional.
The formal calculation looks like this (for the full step-by-step walkthrough with a worked calculation and explicit assumptions, see How to Calculate GEX):
Here Γi is option gamma per $1 underlying move, OIi is contract open interest, Mi is the correct contract multiplier, and di is the assumed dealer-position sign. Every strike uses the same underlying spot S. Multiplying by 0.01 expresses dollar-delta notional per 1% move; an unadjusted US equity option generally has multiplier 100.
Standard GEX counts call gamma as positive and put gamma as negative. The convention reflects the typical structural book: customers overwrite calls and buy protective puts, leaving dealers net long calls and net short puts. It describes structural exposure, not any dealer's actual book.
One Calculation With Explicit Units
Hypothetical example prepared October 16, 2026: a long call has gamma 0.02 per $1, OI 1,000, multiplier 100 and underlying spot $100. Its positive contribution is 0.02 × 1,000 × 100 × 1002 × 0.01 = $200,000 per 1% move. An equal contribution assigned a short-dealer sign would subtract $200,000. Every strike uses the same underlying spot; replacing spot with each strike changes the calculation.
Open interest does not reveal who owns each side. The calls-positive/puts-negative convention models dealers as long calls and short puts; that is an assumption, not observed dealer inventory. A long option has positive gamma whether it is a call or a put; a short option has negative gamma. For the full derivation, see the GEX formula and worked example.
Read a Dated Profile, Then Test Its Limits
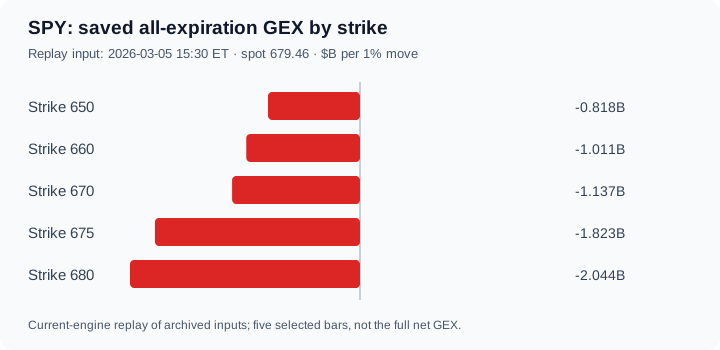
Saved current-engine replay at 2026-03-05 15:30 America/New_York, all expirations. Five largest absolute strike contributions at the same spot, 679.46; these selected bars do not equal total GEX and do not locate a flip. Request, assumptions and hashes.
The full saved SPY response has net GEX −$14.5045B per 1% move and numeric flip 687.1717. It is a current-engine replay of archived inputs, not a current quote or JSON captured that day. The fixture predates flip-certification fields. Counterexample: a negative modeled book can coexist with a rising market when buying pressure or news dominates. The profile does not forecast direction or demonstrate a profitable trade.
How does dealer gamma hedging work?
Think of options dealers as a thermostat for the stock market. When gamma exposure is positive, the thermostat is working, it cools things down when the market heats up and warms things up when the market cools. When gamma exposure is negative, the thermostat is broken, it blasts heat when it is already hot and cranks the AC when it is already cold.
Here is why:
Positive Gamma: The Stabilizer
When net GEX is positive, dealers are net long options gamma. As the stock rises, their hedge requires selling stock into the strength. As the stock falls, their hedge requires buying stock into the weakness. The result? Dealers automatically buy dips and sell rallies, dampening volatility and keeping price in a range.
Negative Gamma: The Amplifier
When net GEX is negative, the dynamic flips. As the stock falls, dealers must sell more stock to stay hedged. As it rises, they must buy more stock. This creates a feedback loop where dealers chase price in the same direction as the move, amplifying volatility.
Positive Gamma Environment
Dealers buy dips and sell rallies
Volatility is suppressed
Price tends to mean-revert within a range
Moves are slow and orderly
Intraday reversals are common
Negative Gamma Environment
Dealers sell dips and buy rallies
Volatility is amplified
Price trends and breakouts dominate
Moves are fast and disorderly
Gap fills and momentum cascades are common
This is why understanding the gamma regime matters far more than trying to predict direction. GEX does not tell you where the market will go, it tells you how the market will behave when it gets there.
The Gamma Flip Point
The gamma flip point (sometimes called the "gamma pivot" or "zero-gamma line") is the price level where aggregate GEX switches from positive to negative. It is one of the most important numbers in options-driven market analysis.
The Gamma Flip Rule
Use the sign of net GEX at the actual underlying price and inspect the flip status. Some portfolios have no stable crossing or multiple crossings; the familiar above-positive/below-negative orientation must be verified, not assumed.
SPY and SPX observations can have a usable flip, no crossing or an unstable/multiple-crossing profile. Check the actual modeled sign and status instead of assuming a universal relationship between above/below the flip and volatility.
Gamma can contribute to different price behavior, but a selloff, rebound or volatility change does not establish gamma as its cause. News, liquidity, volatility repricing and other order flow can dominate the estimated hedge response.
A Worked SPX Gamma-Flip Example
Consider a hypothetical SPX options snapshot. Revalue every included option at a range of possible index prices, keeping the expiry set, open interest, implied-volatility assumptions and dealer-position sign convention consistent. Suppose the resulting aggregate GEX is −$0.6 billion per 1% move at 5,990 and +$0.4 billion at 6,010.
A linear interpolation gives an approximate zero crossing of 6,002: 5,990 + [0.6 / (0.6 + 0.4)] × 20. Recalculating the full portfolio around 6,002 refines that estimate. This is a crossing on a portfolio GEX versus hypothetical spot curve, not the point where neighbouring strike bars change colour on a GEX-by-strike chart.
If actual SPX is 6,008, this example places it on the positive side of that modelled crossing. If it falls to 5,996, the model places it on the negative side. That changes the estimated hedging response; it does not predict the next price move. Real curves can have multiple crossings or none, and a change in volatility, positions or the expiries included can move the estimate.
Use the same timestamp and expiry scope when comparing snapshots. For the underlying aggregation method, see how to calculate gamma exposure. OIC's explanation of gamma covers how delta sensitivity changes near the strike and expiration.
Call Walls and Put Walls
These are method-dependent call/put concentrations, separate from a portfolio gamma flip. FlashAlpha's levels calculation favors out-of-the-money call strikes at or above spot and put strikes at or below spot, with smoothing for dense ATM clusters. Its wall fields are distinct from the largest positive/negative net-GEX strikes.
Call Wall
A call-side concentration. Under a representative long-call dealer assumption, delta hedging can oppose a rally; the concentration does not guarantee resistance.
Put Wall
A put-side concentration. A dealer short puts has negative gamma and may sell after a decline; a dealer long puts has the reverse hedge response. The wall alone does not establish automatic buying or a floor.
Read the levels reference and saved API example. Price can breach a concentration because other flow dominates, positions change or the model assumptions fail. Gamma does not vanish merely because price crosses a strike.
How to Read a GEX Chart
A GEX chart can look intimidating the first time you see one. Here is how to break it down step by step:
Identify the bars
Each bar is a contribution at a strike, at the same current underlying price. Check whether the chart separates call and put contributions or shows their net, and read the sign convention and unit scale. A bar is not a measured hedge order.
Find the current spot price
Look for the vertical line or marker showing where the stock is currently trading. Everything to the right of spot is out-of-the-money calls (and in-the-money puts). Everything to the left is out-of-the-money puts (and in-the-money calls).
Locate the call wall and put wall
Use the provider's wall methodology or explicit wall fields. FlashAlpha's call_wall and put_wall are not automatically its tallest positive and negative net-GEX bars.
Check the gamma flip line
A marked flip represents a hypothetical underlying-price zero crossing of the repriced portfolio, not the point where strike bars change sign. Verify its status and orientation; missing or unstable crossings remain unavailable.
Read the net GEX value
Net GEX gives the modeled aggregate sign and size at the actual price. Positive and negative values imply different conditional hedge sensitivities, while a small net value may conceal offsetting gross exposures. It does not establish future volatility by itself.
Note the expiration context
Near-expiry exposure can be concentrated, especially around at-the-money strikes. If a large expiration is approaching (monthly, quarterly), compare the expiry-specific and full-chain profiles; far-out-of-the-money gamma need not increase.
Trading with Gamma Exposure
The following strategy categories are hypotheses to test under a modeled gamma regime. The sign alone does not establish an edge; include execution costs, events and losing observations.
Positive Gamma: Mean-Reversion Strategies
When modeled net GEX is positive, range-oriented rules are hypotheses to test:
Fade moves toward the call wall and put wall, price is likely to reverse at these levels
Use tighter stop losses, moves are smaller and more predictable
Expect low-range days and closing prices near the open
Negative Gamma: Momentum and Breakout Strategies
When modeled net GEX is negative, momentum-oriented rules are hypotheses to test:
Trade with the trend, do not try to catch falling knives
Buy premium (long straddles, long puts), realized volatility tends to overshoot implied
Use wider stops, moves are larger and less predictable
Be prepared for gap moves and intraday trend days
GEX is not a standalone trading signal. It is a regime indicator that tells you the market's likely behavior, not its direction. Always combine gamma exposure data with your existing analysis, price action, volume, macro context, and risk management. Traders who use GEX as a "buy here, sell here" tool are misusing it.
Key Levels to Watch
Level
Meaning
Trading Implication
Call Wall
Method-dependent call concentration
Conditional reference; verify the observed price response
Put Wall
Method-dependent put concentration
Conditional reference; position signs determine hedge response
Gamma Flip
Net GEX = 0
Check crossing orientation, status and net GEX at actual spot
Expiry scope
The contracts included in the calculation
Match scope before combining GEX and levels
GEX and Market Events
Gamma exposure is not static. It shifts dramatically around certain market events, and understanding these shifts gives you an edge.
Options Expiration (OPEX)
The most important event for GEX. As options expire, the gamma at those strikes disappears, often called a "gamma unpin." If a large amount of positive gamma expires, the stabilizing force is removed, and price is free to move in a direction that was previously suppressed. Monthly and quarterly OPEX (the third Friday of the month) are the most significant, but weekly expirations matter too.
Measure the expiry effect
Compare the same portfolio before and after removing the expiring contracts. The change depends on the signed exposures removed; no universal expiring percentage or post-OPEX volatility multiple is established here.
FOMC and Macro Events
Events can change IV, trade flow and estimated positions. An options trade can open, close or transfer risk; volume alone does not identify an OI increase. Compare matched timestamps and scopes, and do not attribute a post-event price move to gamma without evidence.
Zero-Day Options (0DTE)
The rise of 0DTE options, contracts that expire the same day they are traded, has fundamentally changed intraday gamma dynamics. These options have extremely high gamma because of their short time to expiration. On any given day, 0DTE volume in SPX can represent a massive portion of total gamma exposure.
The result is that intraday GEX levels shift in real time, creating fast-moving support and resistance levels that did not exist even a few years ago. Traders who only look at end-of-day GEX snapshots miss the intraday dynamics driven by 0DTE flows.
Common Misconceptions About GEX
Gamma exposure has become a popular topic, and with popularity comes misunderstanding. Here are the most common myths:
Myth 1: GEX Predicts Direction
GEX does not tell you whether the market will go up or down. It tells you the volatility regime, whether moves will be small and mean-reverting or large and trending. Direction still comes from fundamentals, sentiment, and order flow.
Myth 2: GEX Levels Are Precise Price Targets
Call walls and put walls are zones, not exact numbers. Dealer hedging is spread across a range of strikes and expirations. Treat GEX levels as areas of influence, not precise support/resistance lines. A call wall at $590 does not mean price will stop at exactly $590.00.
Myth 3: GEX Is Only for Day Traders
While intraday traders use GEX the most, swing traders and even portfolio managers benefit from understanding gamma regimes. Knowing whether the market is in positive or negative gamma helps you size positions, choose strategy types, and time entries around OPEX cycles.
Myth 4: All GEX Data Is the Same
Different providers calculate GEX differently. The sign convention (whether put gamma is positive or negative), the assumption about dealer positioning (are dealers always short options?), and the data source (OPRA vs. exchange-specific) all affect the output. Always understand the methodology behind the data you are using.
For a quick reference, inspect an available SPY public gamma snapshot or QQQ snapshot and read the displayed observation time. A public snapshot and authenticated API access have different requirements.
Choose an eligible workflow
Free: a supported individual equity, such as AAPL, and one listed GEX expiry after today; 5 requests/day. SPY/QQQ single-expiry API access: Basic and above. Full-chain GEX: Growth and above. 0DTE and supported CME futures: Growth and above. Historical replay: Alpha and above.
For a complete worked research path, use the complete GEX guide. The developer dashboard tutorial includes a saved fixture, nested levels parsing, matching expiry scopes and errors. Start there instead of copying an undated SPY request and assuming it is Free.
Frequently Asked Questions
GEX estimates how an options book's dollar delta changes for a specified underlying move. This guide uses dollars per 1% move. Dealer signs are inferred under a stated convention; GEX does not directly measure every dealer's inventory or executed hedge.
A delta-neutral long-gamma position tends to require selling underlying after rises and buying after falls; a short-gamma position tends to require the reverse. Actual hedging depends on inventory, execution and other risks.
The gamma flip is a hypothetical underlying price where aggregate GEX crosses zero after repricing the included options. Keep expiry scope, open interest, volatility assumptions and dealer-position signs fixed. It is not a cumulative sum of the current strike bars. A crossing can be absent, multiple or unstable; inspect gamma_flip_status and the net GEX at the actual price rather than assuming that every price above a flip is positive gamma.
They are method-dependent call and put concentrations. FlashAlpha's levels response separates call_wall and put_wall from max_positive_gamma and max_negative_gamma. A wall may be useful context, but is not guaranteed support or resistance.
Neither. The modeled sign describes hedge sensitivity, not the direction of the next price move. Positive-gamma hedging can oppose both rises and falls; other flows can overwhelm it.
A regime describes the sign of modeled aggregate gamma under a particular timestamp, scope and sign convention. An unavailable flip or uncertain status must remain distinct from a certified regime.
Negative net GEX represents an estimated short-gamma book under the stated position convention. It does not prove actual dealer inventory. Check timestamp, expiry scope and sign assumptions; being below an arbitrary flip is not sufficient.
Related Reading
When not to sell options - negative-gamma days held most short-premium losses on SPY and QQQ, 2022 to 2026
Flow-Signed GEX (polarity=flow), sign gamma by the measured dealer position from the classified tape to see if dealers are actually long or short gamma
Crypto Options Dealer Positioning, why bitcoin gamma splits across CME, the spot ETFs and the equity proxies, and why the wrappers routinely disagree on the sign
Conclusion
Gamma exposure is one of the most important concepts in modern market structure. It explains why prices pin to certain levels, why volatility clusters, and why selloffs accelerate. The core idea is straightforward: options dealers are forced to hedge, and their hedging creates predictable patterns in stock prices.
Use one unit convention, keep the dealer-position assumptions visible, and compare observations at matched timestamps and expiry scopes. A flip can be unavailable and a wall can fail. A working, eligible first request is the next step toward evaluating whether GEX helps your particular workflow.
You do not need to become a derivatives mathematician to use GEX effectively. You just need to check the regime before you trade, know where the key levels are, and adjust your strategy accordingly. That single habit will put you ahead of the vast majority of market participants who still trade without understanding the forces that actually move prices.